2027–2031 Canadian Mortgage Outlook

General Trish Pigott 6 Oct

2027–2031 Canadian Mortgage Outlook

Based on the Bank of Canada’s latest position, current Canadian bond yields, and the recent change in economists’ forecasts, I would not be telling clients that materially lower mortgage rates are coming in 2027. The environment has changed. Rates are likely entering a “higher-for-longer, but not crisis-level” period, with variable rates potentially drifting upward and fixed rates remaining volatile.

As of September 2, the Bank of Canada is holding its policy rate at 2.25%, with typical prime around 4.45%. The Bank says inflation risks have increased because of energy prices, geopolitical conflict, tariffs and counter-tariffs, even though underlying/core inflation has remained near 2%.

At the same time, the Government of Canada 5-year bond yield was about 3.63% on October 5, which is important because it is a major pricing influence on 5-year fixed mortgages. Canadian lenders have already been responding: the Big Six have recently increased fixed mortgage pricing as bond yields rose.

These are planning ranges, not predictions of specific lender rates. Mortgage pricing depends on borrower type, insurance status, loan-to-value, lender spreads and promotions.

Year BoC Policy Rate – planning range Variable Mortgage – rough range 5-Year Fixed – rough range My view
2027 2.50–3.00% 3.6–4.4% 4.2–5.1% Rates likely edge higher
2028 2.75–3.25% 3.9–4.7% 4.1–5.1% Normalization
2029 2.75–3.25% 3.9–4.7% 4.0–5.0% More stable
2030 2.50–3.25% 3.7–4.7% 3.9–5.0% Stable/moderate
2031 2.50–3.25% 3.7–4.7% 3.9–5.1% “New normal”

Rates will land roughly around 4.5 – 5.5% as the central planning zone for Canadian mortgage rates over the next five years, we will not see a return to the ultra-low 2–3% fixed mortgages of the pandemic era.

There is significant uncertainty around those ranges. Earlier Bank of Canada market-participant forecasts had the 5-year Government of Canada bond yield around 3.1% at the end of 2027, but the actual benchmark has recently been around 3.6%, illustrating how quickly the outlook has repriced.

1. Variable rates: the story has changed

The argument for variable mortgages through 2024–26 was straightforward: inflation was falling, the Bank of Canada was cutting, and borrowers could benefit as prime declined.

We are now much closer to the bottom of that rate cycle.

RBC Economics believes rates have effectively bottomed and expects the Bank of Canada eventually to begin raising rates as the economy strengthens. RBC Market-implied forecasts have similarly pointed toward the overnight rate gradually moving from 2.25% toward roughly 2.5–3% over the next several years.

That doesn’t mean variable mortgages are suddenly bad.

In fact, variable is currently attractive because the best discounted variable pricing is below comparable five-year fixed pricing. Current comparison data shows approximately 3.65% variable versus roughly 4.74% for a competitive 5-year fixed, although individual borrowers will see different pricing.

But the reason to choose variable has changed.  You’re getting a lower rate today and greater flexibility, but you need to be financially comfortable if prime increases over the next several years.


2. Fixed rates: we could see more risk

This surprises clients.

We repeatedly hear:

“The Bank of Canada isn’t increasing rates, so why are fixed rates going up?”

Because the Bank of Canada doesn’t directly price fixed mortgages.  Government bond yields and lender funding costs are much more important.

And bond markets have become significantly more concerned about inflation, government borrowing, geopolitical instability and energy prices. Global bond markets recently experienced another major selloff, pushing long-term yields sharply higher.


What could push Canadian mortgage rates higher?

4 Things to watch particularly closely.

Inflation and energy prices. The Bank of Canada says headline inflation has recently been around 3%, largely because of energy, although inflation excluding gasoline has been closer to 2.2%.

Canada–U.S. trade policy. Tariffs are problematic because they can simultaneously weaken economic growth and increase prices. That puts the Bank of Canada in a difficult position.

Government debt and global bond yields. This is the underappreciated risk for fixed mortgages. Even if Canadian inflation behaves reasonably well, higher global yields can keep Canadian fixed mortgage rates elevated.

Geopolitical instability. Energy supply disruptions and conflict can rapidly change inflation expectations. That’s exactly what markets have been experiencing recently.


What we are advising Primex clients right now

When choosing between fixed versus variable, be reminded it’s not about which rate wins.

It is a risk-management decision.

For a financially strong client with good cash flow, emergency savings and tolerance for payment changes, variable can still be very attractive. The current discount relative to fixed gives the borrower some cushion before variable becomes more expensive.

For someone whose budget is tight, particularly a first-time buyer or a household carrying significant consumer debt, I would lean toward fixed or shorter-term fixed. Certainty has value when an extra $200–$400 a month would materially affect the household.

And we think the 3-year fixed deserves particular attention over the next year.

It provides payment certainty through what could be a volatile 2027–28 period without locking someone into today’s environment for a full five years. It gives the borrower another opportunity to reassess in 2029–30.

It’s a smart term to compare with the 5 year fixed rate option to see what the difference is in those rates and terms to determine the best financial choice.


Reminders in today’s market

For the last few years the question has often been:

“When are rates coming down?”

We need to shift that thinking toward:

“What mortgage strategy gives you the best combination of rate, flexibility and protection if rates don’t come down?”

For renewals, homeowners should be looking at three scenarios:

Variable: Today’s payment + payment at prime +0.50% and +1.00%.

3-year fixed: Payment certainty with an earlier opportunity to reprice.

5-year fixed: Maximum payment certainty, but with careful attention to penalty structure and flexibility.

When deciding, ask yourself:

“Which of these payments would you still be comfortable carrying if the economy doesn’t cooperate?”

That will help your decision rather than guessing what interest rates will do and lead toward proper mortgage planning.


When Planning, consider these assumptions:

2027: Slightly higher rates are more likely than significant cuts.

2028–29: Policy rates probably settle somewhere around a neutral 2.75–3.25% range unless Canada enters recession.

2030–31: Mortgage rates probably normalize, but I would still expect conventional fixed mortgage rates broadly around 4–5% rather than 2–3%.

RBC’s current housing outlook similarly says interest rates have likely reached their cyclical bottom and expects some upward pressure on longer-term rates through 2027.

The biggest wild card is recession. A significant Canadian/U.S. downturn would change this forecast quickly: the Bank of Canada could cut rates and bond yields could fall, which would favour variable borrowers and eventually pull fixed rates lower.

But… another inflation shock could push both substantially higher like what we saw in 2022.

Our message;

Don’t wait for the perfect rate. Build the right mortgage strategy.

For clients buying or renewing in 2027, our advise is that we can not predict the lowest rate and will help you compare options that stress-tests the mortgage against several possible rate environments and chooses the term that best protects the household.

That’s why our goal is to always be Guiding Canadians Home with more valuable conversations rather simply quote rates.

We are here for those conversations so if you want to talk more specifically about your household and mortgage BOOK HERE for a 15 minute phone call. 

Buying a Vacation Home with Family?

General Trish Pigott 1 Sep

Buying a Vacation Home With Family in BC

Key things to discuss before you buy

  1. Decide exactly who is buying the property
  • Who will be registered on title?
  • Who will be borrowers on the mortgage?
  • How much is each person contributing to the down payment?
  • Will everyone own an equal percentage?
  • If one person contributes more, does that mean they own more?
  • Is anyone contributing money but not going on title?
  • Remember that mortgage liability and ownership percentages are separate issues. A lender may require borrowers to be jointly responsible for the entire mortgage even if their ownership shares differ.

2. Decide how title should be registered

In BC, two common forms of co-ownership are:

Joint Tenancy

  • Each owner has an undivided interest in the property.
  • Includes a right of survivorship.
  • If one owner dies, their interest generally passes to the surviving joint owner(s), rather than through their estate.
  • Often used between spouses.
  • It can become complicated when siblings, parents, adult children or multiple family units are purchasing together.

Tenancy in Common

  • Each owner has a defined ownership interest.
  • Ownership does not have to be equal.
  • For example:
    • Parents – 50%
    • Adult Child #1 – 25%
    • Adult Child #2 – 25%
  • An owner’s share generally becomes part of their estate when they die rather than automatically passing to the other owners.
  • This structure can provide greater clarity for unrelated owners or extended-family purchases.

For many multi-family vacation-home purchases, tenancy in common is worth discussing with the buyers’ lawyer, particularly where contributions or intended ownership percentages differ.

3. Have a written Co-Ownership Agreement

This is probably the most important recommendation.

Family members may get along extremely well today, but circumstances change. A lawyer-drafted Co-Ownership Agreement can establish the rules while everyone is still on good terms.

The agreement should address:

  • Percentage owned by each person
  • Initial down-payment contributions
  • Responsibility for the mortgage
  • Property taxes
  • Insurance
  • Utilities
  • Strata fees, if applicable
  • Repairs and maintenance
  • Major renovations
  • Furniture and improvements
  • How annual expenses are divided
  • Whether a reserve/emergency fund will be maintained
  • Who manages the bank account and pays bills
  • How decisions are made
  • What requires unanimous approval versus majority approval

It should also address how the family actually gets to use the vacation home:

  • How weeks/weekends are allocated
  • Holidays and long weekends
  • Whether owners can bring guests
  • Whether friends can use it without an owner present
  • Pets
  • Cleaning responsibilities
  • Damage caused by guests
  • Whether the property can be rented
  • Who receives rental income
  • Who manages rentals and related expenses

4. Have an exit strategy before purchasing

This is the area families often overlook.

Agree in advance on what happens if someone:

  • Wants to sell their share
  • Can no longer afford their share
  • Gets divorced or separates
  • Dies
  • Becomes incapacitated
  • Moves away
  • Has financial difficulties
  • Stops contributing to expenses

The agreement should establish a buyout process, including:

  • Does the family get the first opportunity to purchase the departing owner’s share?
  • How will the property be valued?
  • Will you use one appraisal or multiple appraisals?
  • How long does everyone have to complete a buyout?
  • Can an owner sell their interest to an outsider?
  • What happens if nobody can afford to buy them out?
  • At what point must the entire property be sold?

This is particularly important because BC’s Partition of Property Act provides mechanisms through which parties with interests in land can seek partition or sale of jointly owned property. (BC Laws)

In other words, “we’ll just figure it out if someone wants out” isn’t a great exit plan.

5. Consider death and estate planning

Every owner should review their Will and estate plan at the time of purchase.

This becomes particularly important with tenancy in common.

For example, imagine two sisters buy a cabin 50/50. One sister dies and leaves her estate to her children. The surviving sister could suddenly find herself owning the vacation home with her nieces and nephews.

The co-ownership agreement and each owner’s estate plan should therefore work together.

Ask the lawyer about:

  • Right of first refusal
  • Buyout rights upon death
  • Life insurance to fund a buyout
  • Whether ownership should pass to heirs
  • Whether spouses can inherit an interest
  • How joint tenancy versus tenancy in common affects the intended estate plan

6. Understand the tax implications

Don’t assume a vacation property will automatically be tax-free when it is eventually sold.

A cottage or vacation home can potentially qualify as a principal residence, provided CRA’s requirements are met, but generally only one property per family unit can be designated as a principal residence for a particular year. (Canada)

That means owners who already own their primary homes should obtain tax advice about:

  • Future capital gains
  • Adjusted cost base
  • Tracking renovation and improvement costs
  • Rental income, if applicable
  • Principal residence designation
  • Changes in use
  • What happens tax-wise when an owner dies or transfers their interest

Keep records and receipts for major capital improvements from day one.

7. Understand the mortgage implications

This is another important conversation before writing an offer.

Depending on the lender and structure:

  • All owners may need to be included in the mortgage application.
  • All borrowers may be jointly responsible for the mortgage.
  • One person’s debts or credit situation can affect qualification.
  • Removing someone from title later isn’t necessarily as simple as signing their name off.
  • The remaining owners may need to requalify for the mortgage.
  • A transfer of ownership may involve legal fees, lender approval and potentially tax consequences.
  • Future borrowing capacity for each person may also be affected because the vacation-home mortgage is part of their overall liabilities.

8. Talk about the uncomfortable scenarios now

Before purchasing, I would encourage every family to answer one simple question:

“What happens if our relationship or financial circumstances are completely different five years from now?”

The goal isn’t to expect problems. It’s to make sure a financial disagreement never has to become a family disagreement.

Recommended professional team

Before removing subjects, I’d recommend the family speak with:

Mortgage Broker → BC Real Estate Lawyer/Notary → Accountant/Tax Advisor → Estate-Planning Lawyer

Ideally, the legal agreement is prepared before or alongside the purchase, rather than after everyone is already on title.

Bottom line: For a vacation property being purchased by siblings, parents/adult children, or multiple family households, I would generally encourage them to specifically discuss tenancy in common + a comprehensive co-ownership agreement + updated Wills with their BC lawyer before deciding how title will ultimately be registered.  Get advice from your lawyer when deciding what suits your family best. 

This is general information rather than legal or tax advice;

The right structure depends heavily on who is contributing the money, who will use the property, and what everyone wants to happen to their share in the future.  

Leasehold Property – Updates and What You Need to Know

General Trish Pigott 25 May

Leasehold Properties in BC – Pros & Cons Explained

A leasehold property means you own the home or unit, but you do not own the land underneath it.
Instead, you lease the land from the landowner for a set period of time (example: 30, 50, 75, or 99 years).

Leasehold properties are commonly found on:

  • First Nations land
  • City-owned land
  • University lands
  • Resort communities
  • Some condo developments

Pros of Buying a Leasehold Property

Lower Purchase Price

  • Leasehold properties are often much less expensive than freehold properties
  • Can help buyers enter the market sooner
  • Allows buyers to purchase in areas that may otherwise be unaffordable

Lower Down Payment Needed Overall

  • Since the purchase price is lower, buyers may need less cash upfront
  • Monthly mortgage payments can sometimes be lower as well

Opportunity to Own in Desirable Locations

  • Leasehold homes are often located in prime areas near:
    • Waterfronts
    • Downtown cores
    • Universities
    • Golf courses
    • Resort communities

Good Option for Shorter-Term Ownership

  • Can work well for buyers who:
    • Want affordability
    • Do not plan to stay long term
    • Are purchasing for lifestyle reasons

Some Leaseholds Include Maintenance Benefits

  • Depending on the development, some costs may already be included in lease payments or strata fees

Cons of Buying a Leasehold Property

You Do Not Own the Land

  • This is the biggest difference
  • The land remains owned by another party
  • You are paying for the right to use the land for a specific time period

Financing Can Be More Difficult

  • Not all lenders finance leasehold properties
  • Fewer lender options may mean:
    • Higher rates
    • Larger down payment requirements
    • Shorter mortgage terms
  • Some lenders will not finance properties with shorter remaining lease terms

Resale Can Be More Challenging

  • Leasehold properties can take longer to sell
  • Buyers are often unfamiliar with leaseholds
  • The shorter the remaining lease, the harder resale may become

Property Value May Not Increase the Same Way

  • Leasehold properties may appreciate slower than freehold properties
  • As the lease gets shorter, value may decline

Lease Payments May Increase

  • Some leaseholds require monthly or annual lease payments
  • Certain leases have scheduled increases over time
  • Buyers should review:
    • Current lease payment
    • Future increases
    • Lease expiry date

Lease Expiry Matters

  • The closer the property gets to lease expiry:
    • Financing becomes harder
    • Property values can decrease
    • Buyer demand may shrink

Restrictions May Apply

  • Some leasehold agreements may limit:
    • Renovations
    • Rentals
    • Pets
    • Property use
    • Subletting

Important Questions Buyers Should Ask

Before purchasing a leasehold property, buyers should confirm:

  • How many years remain on the lease?
  • Who owns the land?
  • Are lease payments fixed or adjustable?
  • Are there future lease increases?
  • Are there restrictions on the property?
  • Which lenders will finance it?
  • What happens at lease expiry?
  • Is the lease renewable?

Good Candidates for Leasehold Properties

Leasehold properties may work well for:

  • First-time buyers wanting affordability
  • Buyers focused on location over long-term appreciation
  • Buyers comfortable with shorter ownership timelines
  • Investors familiar with leasehold risks
  • Buyers looking for vacation or recreational properties

Final Thoughts

Leasehold properties can offer excellent value and affordability, but buyers must fully understand:

  • The lease terms
  • Financing limitations
  • Future resale implications
  • Remaining lease length

The key is reviewing the lease agreement carefully and making sure the property still fits your long-term goals and budget.

For personalized guidance on leasehold financing options across BC, please contact:

Trish Pigott
Mortgage Broker at Dominion Lending Centres Primex Mortgages
📞 604-729-7940
🌐 www.trishpigott.com


Serving clients across BC

April 2025 Rate Announcement

General Trish Pigott 4 Jun

The Bank of Canada left rates unchanged as there was not enough reason to make another reduction given everything that is going on economically across the country and down south. The bank noted that the unpredictability of what’s happening with tariffs, lowered the risk to growth and a possible increase to inflation, determining that they were going to pause any further rate cuts until they see more data and the outcome so far.

Bottom Line according to Dr. Sherry Cooper, DLC’s own economist;

The US is determined to impose worldwide tariffs, disproportionately hitting Canada, Mexico, and China, the US’s top trading partners. This is a misguided neo-Mercantilist policy. Mercantilism assumes that the global economic pie is fixed, so if one country prospers, another must fail. This idea of a zero-sum game was debunked in the 18th century by Adam Smith and others who showed that if countries have a competitive advantage in various products and services, all are better off by producing and trading those products with the rest of the world. It is not a zero-sum game. The economic pie grows with trade. This was the idea behind globalization and the USMCA free trade agreement.

Given Canada’s vulnerability to tariffs, the economy will suffer more than the US, which has a relatively closed economy (where exports are a small proportion of GDP). Prices will rise depending on the duration and size of the coming tariffs, but mitigating the inflation will be the weakness in economic activity. Stagflation, a buzzword from the 1970s, is back in the lexicon.

We expect the BoC to resume cutting the policy rate in 25-bps increments until it reaches 2.0%-to-2.25% this summer, triggering a rebound in home sales. Layoffs and spending cuts will dampen sentiment, but lower interest rates will bring buyers off the sidelines. Housing inventories have risen sharply with new condo supply and a marked rise in the new listings of existing homes, and home prices are falling.

Because the pathway with tariffs is still unclear, the BoC decided in April on a wait and see approach. Our next Bank of Canada announcement is June 4 so we will have further insight and data to determine what will happen at that point.

Tariffs and Your Mortgage

General Trish Pigott 6 Mar

UPDATE 3/6/25: Just as I was about to send this apparently Trump has paused the tariffs to Mexico and now Canada until April 2.  Good grief….how does anyone keep up with this…either way here are some tips below if he is back at it next month on how to handle your mortgage and potentially take advantage of falling rates.

On Tuesday, March 4, 2025 Trump has imposed tariffs of 25% on goods coming from Mexico and Canada, 10% on Canadian energy, and an additional 10% on goods from China and has since already scaled back on 3 automotive suppliers.  Canada has come back with retaliatory tariffs and now we end up in a trade war with the US. There is so much debacle with the entire Trump administration, it’s mind blowing that this is where we are in todays day and age.

Over the last few days we’ve seen a wild ride in the stock markets and as a result the bond market has fallen which directly affects fixed mortgage rates.  We have not seen the bond market this low since mid 2022.  We have also had multiple economists report yesterday and today that the Bank of Canada will respond with additional rate cuts to the overnight target rate (which affects the Prime rate) and now expected that we will see 4 more cuts by July of this year with the first one next week.

How does this affect mortgage holders; 

  • New Mortgage Borrowers:  This will allow you to qualify for slightly larger mortgages and give lower payments in either a Variable Rate Mortgage or Fixed Rate Mortgage as rates drop
  • Existing Variable Rate Mortgage Borrowers: This will lower your mortgage rate when Prime comes down and in some cases lower mortgage payments.
  • Existing Fixed Rate Mortgage Borrowers: Potential opportunity to reduce your current rate by either Refinancing your mortgage or Switching your mortgage to a new lender at a lower interest rate improving your cash flow.
  • Although lower mortgage rates are usually a positive thing for home owners, buyers and the real estate market in general, this is a very difficult time for our economy.  There are so many unknowns and we do not want to repeat what happened during the pandemic years with rock bottom rates and then a rate spike.
Reminders on moving forward: 
  • Although lower rates generally equal lower payments, this is a time to build up your savings and not to overspend
  • Even though home buyers may qualify for more, be very aware of not over extending to protect your financial future
  • If you are Refinancing or Switching to get a lower rate, try and leave your current payment the same so that you are paying your mortgage and interest down that much faster
  • Be reminded that during the pandemic, many people maxed out their budgets with low mortgage payments and had excessive cash which was used to overspend in many cases in housing and consumer spending in general.  Be very careful not to get caught in that trap.
  • This drove up inflation substantially which ultimately caused the Bank of Government to increase rates in a short period of time putting a massive strain on many households financially due to rising mortgage payments

So in summary, while we may see lower rates over the course of this year, be very diligent with your spending habits right now as we see how everything will unfold with our borders and overall economy.

Now more than ever is the time to get your finances in order to prepare and plan. To get started and put a plan in place, contact me directly at 604-729-7940.

We are watching this daily and I will have an update out next week with the Bank of Canada’s next rate announcement on March 12, 2025.

First Bank of Canada Announcement of 2025

General Trish Pigott 12 Feb

On January 29, 2025, there was some welcoming news from the Bank of Canada (BoC) as they kicked off the first announcement of the year with a .25% rate cut.  This affects our Variable Rate mortgage holders and anyone with loans attached to the prime rate.

As of tomorrow the Prime rate with most banks is coming down to 5.20% which is bringing new variable rate mortgages to the range of 4.20% and 4.90% depending on what lender and the property type.  If you have an Adjustable Rate Mortgage (ARM) this means your payment will come down by roughly $15 for every $100,000 in mortgage amount.  If you have a Variable Rate Mortgage (VRM) then your payment will not change but you will be paying down your principal faster and less towards interest.

The BoC feels that the 2% in rate drops since mid last year has done it’s job that it intended to do which as a result has brought inflation down to a more comfortable level at 1.8%  South of the border today, they also had a rate announcement and did not reduce rates as inflation is on the rise down south.  Our next announcement is March 12 where it is expected that the BoC will leave rates unchanged as everything unfolds however we are still expecting that we should see another .50% in rate drops by mid this year.  That would put the variable rate at roughly around the 4% range.

Below is a snapshot from Dr. Sherry Cooper’s report today, DLC’s Chief Economist, outlining where rates are expected to go in the first half of 2025.


If you would like to read the full article from Dr. Sherry Cooper, check out our blog post and  CLICK HERE

Energy Efficiency Rebate: A Hidden Benefit

General Trish Pigott 25 Nov

Did you know about these valuable opportunities for buyers of New Construction property with an Insured Mortgage? 
Energy Efficiency Refund: A Hidden Benefit
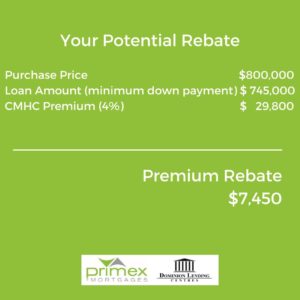
Clients securing an insured mortgage for a new build with energy-efficient certification are eligible for a 25% refund on the default insurance premium.
  • In British Columbia:
    Most new builds must meet BC Energy Step Code requirements as of May 1, 2023, which means nearly all qualify for this refund.
  • Surprising Stats:
    75% of eligible buyers don’t apply for this refund—often because they aren’t informed or their broker hasn’t advised them.
Buyers have two years from the mortgage start date to apply, and the program is offered by CMHC, Sagen, and Canada Guaranty.  If you bought a new construction property in the past 2 years and paid for mortgage default insurance, you may still have time to apply.
Why This Matters Now
The 30-year amortization option for first-time homebuyers (FTHBs) purchasing new builds took effect on August 1, 2024. This aligns perfectly with the refund program, as buyers may be more likely to purchase energy-efficient properties.

This program applies to all buyers—not just FTHBs—purchasing energy-efficient new builds with insured mortgages.

Resources for Applying
It’s easy to apply, and refunds are processed quickly. Below are direct links to insurer information and applications:
If you have any questions or need further assistance, feel free to reach out to us at the office.
Thank you to our partners at MCAP and Lisa for sharing this important reminder to our clients.

Tips to Pay off Your Mortgage Faster

Mortgage Tips Trish Pigott 25 Sep

Paying off your mortgage faster in Canada can save you a significant amount in interest and help you become debt-free sooner. Here are the top 5 tips to achieve that:
 
1. Make Biweekly Payments
 
Instead of making one monthly payment, switch to biweekly payments. This results in 26 half-payments, which equals 13 full payments each year instead of 12. That extra payment can significantly reduce the interest over time.
 
2. Pay Extra Toward the Principal
 
Whenever you can, make extra payments that go directly toward the principal balance. Even small additional amounts such as $100 can have a huge impact, especially if done consistently over the life of the loan. Usually you can make lump sum payments up to 15-20% of your original mortgage amount without penalty.
 
3. Refinance to a Lower Interest Rate
 
Refinancing from a higher rate to a lower rate can significantly reduce the interest paid over time. Although you may have to pay a penalty to change the mortgage, often you will save and pay less interest in the long run.
 
4. Round Up Your Mortgage Payment
 
Round up your regular mortgage payment to the next $100. For instance, if your bi-weekly payment is $1321, round it up to $1400. Chances are you won’t even remember you did it a month later and that extra amount goes straight to principal.
 
5. Shorten the Amortization Period
 
When your mortgage renews, try to shorten the length of your amortization period (e.g., from 25 years to 23 or even 20 years) can dramatically lower the total interest paid and get you mortgage-free faster.
 
By following these strategies, you can minimize interest and accelerate the path to being mortgage free faster!

Bank of Canada Rate Cut – September 2024

General Trish Pigott 4 Sep

Excellent news as we wrap up summer, the Bank of Canada (BoC) has cut rates again this morning by another .25%.  This change affects Variable Rate Mortgage holders and anyone with loans attached to the banks Prime Rate.

Lots of news today.  Both in Canada and the US. Both the 5-year Gov’t of Canada bond yield and the 10-year US Treasury are down this morning on all this news (this affects the Fixed Rate Mortgage Market).  Good news on adjustable and variable rates in Canada and potentially (hopefully) fixed rates down the line.

Let’s start with Canada.  As expected, the Bank of Canada lowered to 4.25%, which translates into a 6.45% Prime.  Canada’s imports are down over $1 billion in July.  Less imports = less stuff, translates into less discretionary spending.  60% of Canada’s economy is the consumer and when they’re buying less, that translates into potential job losses down the line.

Monetary policy remains restrictive. While the target overnight rate is now 4.25%, core inflation is only roughly 2.4%. Real interest rates remain too high for the economy to reach its potential growth pace of about 2.5%. Weaker growth implies a continued rise in unemployment and excess supply in other sectors.

Now down south; the US released data showing that US job openings fell to their lowest level since January 2021, consistent with other signs of slowing demand for workers.  US job growth has been slowing, unemployment is rising, and job seekers are having greater difficulty finding work, fueling fears about a potential recession.  Federal Reserve policymakers have made it clear they don’t want to see further cooling in the labour market and are widely expected to start lowering interest rates at their next meeting in two weeks.

In other news, consistent with a global economic slowdown, oil prices have plunged to new 2024 lows. Weak oil prices are a sign of lower inflation, growth and mortgage rates.

Does this affect Fixed Rates?  Bonds rallied in the wake of the disappointing US data, taking the 5-year government of Canada bond yield down to a mere 2.89%, well below the 3.4% level posted when the Bank of Canada began cutting interest rates in June. This decline in market-driven interest rates reduces fixed-rate mortgage yields again resulting in lower fixed mortgage rates.

In summary, today’s cut in the overnight rate will be followed soon by a 25 basis point (.25%) reduction in the prime rate to 6.45%, reducing variable and adjustable mortgage rates as well.   This puts a Variable Rate Mortgage today somewhere around 5.65% to 5.45% depending on lender and product.

Looking forward…..The Bank of Canada has two more decision dates this year: October 23 and December 11. At those meetings, the Bank is widely expected to continue its quarter-point rate cuts, taking the overnight rate down to 4.0% at yearend and 2.75% next year.  This is welcoming news to all new and current mortgage holders.

And some more information for those that love this topic from our partners at First National Financial

We summarize the Bank’s rationale for this decision by summarizing its observations below, including its forward-looking comments for signs of what may happen next.

Canadian inflation

  • As expected, inflation slowed further to 2.5% in July
  • The Bank’s preferred measures of core inflation averaged around 2.5%
  • The “share of components” of the consumer price index are growing above 3%, roughly at their historical norm
  • High shelter price inflation is still the biggest contributor to total inflation but is starting to slow. Inflation also remains elevated in some other services

Canadian economic performance and outlook

  • In Canada, the economy grew by 2.1% in the second quarter – led by government spending and business investment – and this rate was “slightly stronger” than forecast in July, but preliminary indicators suggest that economic activity was soft through June and July
  • The Canadian labour market continues to slow, with little change in employment in recent months. Wage growth, however, remains elevated relative to productivity

Global economic performance and outlook

  • The global economy expanded by about 2.50% in the second quarter, consistent with projections in the Bank’s July Monetary Policy Report
  • In the United States, economic growth was stronger than expected, led by consumption, but the labour market has slowed
  • Euro-area growth has been boosted by tourism and other services, while manufacturing has been soft
  • Inflation in both regions continues to moderate. In China, weak domestic demand weighed on economic growth
  • Global financial conditions have eased further since July, with declines in bond yields. The Canadian dollar has appreciated modestly, largely reflecting a lower US dollar. Oil prices are lower than assumed in July

Summary comments and outlook

In making today’s decision, the Bank noted that excess supply in the economy continues to put downward pressure on inflation, while price increases in shelter and some other services are holding inflation up. As a result, Governing Council is “carefully assessing” these opposing forces on inflation. Monetary policy decisions will be guided, therefore, by incoming information and the Bank’s assessment of the implications for the inflation outlook.

And has it has been doing for some time, the Bank said it “remains resolute” in its commitment to restoring price stability for Canadians.”

Feel free to contact me anytime directly to chat about all things mortgages at 604-729-7940

Bank of Canada Rate Cut ~ July 2024

General Trish Pigott 24 Jul

Today the Bank of Canada lowered it’s Overnight Target rate to 4.50% offering a little bit more relief to Canadian consumers suffering under the weight of high mortgage rates and other borrowing costs.  This puts us back to what the rate was in June 2023.

Here’s a few quick highlights I have summarized from a variety of our economists reporting this morning that led to the BoC decision today:

  • The BoC commented that inflation would be less than 2% if it weren’t for the high mortgage interest and shelter costs – this is a good sign as we are getting closer to where they are comfortable
  • Manufacturing sales in Canada plummeted -2.6%, another example of why lower rates will help a struggling economy
  • Economic growth “likely” picked up to about 1.5% through the first half of 2024, however with population growth of about 3%,the economy’s potential output is still growing faster than GDP which means excess supply has increased
  • Household spending is weak
  • Unemployment rates are rising to 6.4% and taking job seekers longer to find work
  • Residential investment is expected to grow robustly
  • New government limits on admission of non permanent residents should slow population growth in 2025
  • Shaves about $15 off monthly payments on your typical new 25-year amortized variable-rate mortgage, per $100,000 borrowed
  • Next announcement is September 4, 2024

Fixed rates are still anywhere from .75% to .90% less than the Variable today so most are still choosing fixed rates which are not necessarily impacted by the Bank of Canada announcements.  Fixed Rates are driven by the bond market which did fall a bit further today so Fixed Rates are trending downward because of this.  Here is a snapshot of how the two have played out for the past 15 years.

Feel free to contact me anytime directly to chat about all things mortgages at 604-729-7940