|
|
|

|
|
Latest News Trish Pigott 28 Oct
|
|
|
|
|
Latest News Trish Pigott 26 Oct
Recent economic forecasts suggest the Bank of Canada may begin increasing interest rates sooner than originally expected, possibly as early as October 28, with further increases in 2027. While nothing has been confirmed, this means we may not see the lower mortgage rates many homeowners were hoping for.
Variable rates: Could increase over the coming months if the Bank of Canada raises its rate.
Fixed rates: Have remained relatively stable recently, but could still fluctuate based on the economy and bond markets.
Mortgage renewals: If your mortgage is coming up for renewal in the next 6 – 12 months, now is a good time to review your options.
Below is a comparison showing how a 0.25% or 0.50% increase in variable mortgage rates could affect homeowners with mortgage balances of $400,000, $600,000 and $800,000.
Assumptions: Starting rate of 3.50%, 25 years remaining, monthly payments, and semi-annual compounding. Calculations assume payments are adjusted immediately to maintain the 25-year amortization.
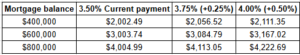
$400,000 mortgage
+0.25% rate increase
$54.03 more per month
+0.50% rate increase
$108.85 more per month
$600,000 mortgage
+0.25% rate increase
$81.05 more per month
+0.50% rate increase
$163.28 more per month
$800,000 mortgage
+0.25% rate increase
$108.06 more per month
+0.50% rate increase
$217.71 more per month
Reminder: Adjustable-rate mortgages generally change payments when rates change. Fixed-payment variable mortgages may instead keep payments unchanged while more goes toward interest and less toward principal, potentially extending the amortization.
Variable mortgage holders: Prepare for the possibility of a 0.50-percentage-point increase over the next several months. Review affordability and payment adjustments now rather than waiting for the Bank of Canada announcement.
Fixed-rate borrowers: Continue comparing three-year and five-year fixed options. There is currently insufficient evidence to conclude that fixed rates will increase significantly in the immediate future.
Homeowners Renewing in 2027: Budget conservatively. The possibility of further rate reductions has weakened, but the evidence does not yet justify substantially increasing our five-year mortgage-rate projections.
The next announcement is October 28, 2026, when the Bank of Canada will announce its interest-rate decision and release updated economic projections.
Reminder: if there is a change, it will be to the Overnight Target Rate which affects the Prime Rate not, Fixed Rates. Fixed Rates could change if the bond market and the dollar are affected so lock in a rate now if you are on the fence or looking at a change to your current mortgage. When in doubt, contact us to lock in your rate.
Our advice? Don’t try to time the market. Time your life and your budget. The lowest rate isn’t always the best mortgage. Choosing the right term, payment structure and flexibility for your personal situation is what matters most.
Latest News Trish Pigott 2 Sep
|
|
|
|
Latest News Trish Pigott 10 Jun
Today the Bank of Canada announced no changes to the overnight target rate. This is directly affecting the prime rate which all banks use to determine variable rate mortgages. Given the instability of our economy due to the events with the US and Iran war, the Bank of Canada is remaining cautious resulting in no changes today. Below is a summary from our call today with Dominion Lending Center’s own Chief Economist Dr Sherry Cooper and our President of Dominion Lending Centers, Eddy Cocciollo.
Today’s press conference was all about balancing two opposing forces on the Bank’s prime rate: rising inflation due to the increase in oil and gas prices, and the currently slumped Canadian economy.
On one hand, the Bank is considering increasing the rate to address inflation. However, so far there “has been limited evidence of broad-based pass-through of higher energy prices to other consumer prices”.
On the other hand, the Bank is considering decreasing the rate to stimulate the economy. However, it does look like the economy is “poised to return to return to growth in the second quarter of 2026”.
The other item of interest in Macklem’s address is CUSMA. Business outlook surveys have shown that Canadian business are done holding their breath on tariff news – and are getting on with business. There has been some increase in business investment which is great. Underlying the tension is a piece of calming news – the July 1st date isn’t a be-all-end-all in negotiations. CUSMA will remain in place through 2036 until it’s officially renegotiated.
Today Dr. Sherry Cooper gave us some great insights on the latest in the Canadian economy. Here’s what you should know:
Bottom Line
The Bank of Canada has shown its willingness to bolster the Canadian economy amid unprecedented trade uncertainty and a record oil price shock. Ottawa, too, has taken actions to reduce the burden of higher prices on Canadians by temporarily eliminating the excise tax on oil. PM Carney is also working to diversify Canada’s trade away from the US, a strategy that has thus far been remarkably successful. As the charts below show, Canadian export diversification is gaining momentum. In addition, goods imports are also shifting away from the US to the rest of the world.
We continue to maintain the view that the Bank of Canada will keep rates steady this year. If inflation broadens and accelerates, rate hikes are possible, but that is not our baseline forecast. The Bank of Canada will be reluctant to tighten into housing market weakness. While housing activity strengthened in May, momentum is muted, and affordability improvements are likely to taper off in the coming months as trade tensions and the war keep oil prices and interest rates elevated.
The above details and Bottom Line are provided by Dominion Lending Centres
Latest News Trish Pigott 29 Apr
Bank of Canada Holds Policy Rate Steady ~ From the desk of Dr. Sherry Cooper, Economist Dominion Lending Centres
Today, the Bank of Canada once again held the policy rate steady at 2.25%. This is the bottom of the Bank’s estimate of the neutral overnight rate, where monetary policy is neither expansionary nor contractionary. With inflation hovering at 2.4% and core inflation falling to 2.0%, the Governing Council sees the current overnight rate as appropriate, as the Bank looks through the inflationary effects of the war in Iran.
“The evolving conflict in the Middle East is causing heightened volatility, and US trade policy continues to reshape global trade patterns. Both are ongoing sources of uncertainty. The Bank’s April outlook assumes tariffs remain unchanged and the global benchmark price of oil declines to US$75 per barrel by mid 2027, still well above pre-war oil prices”. According to the BoC, if that happens, inflation should peak around 3% in April and ease back to the 2% target by early next year.
“The Iran war has led to sharply higher energy prices and transportation disruptions, diminishing growth prospects in oil-importing countries and boosting inflation worldwide. In the United States, growth is still expected to be solid over the projection horizon, boosted by AI-related investment and consumption growth. China’s economy is supported by robust exports. In the euro area, higher prices for oil and natural gas will weigh on economic activity.”
Bond yields are modestly higher since January, while equity markets, which weakened sharply at the outset of the war, have recovered. Since the start of the war, the US dollar has appreciated against most major currencies.
“The outlook for economic growth in Canada is little changed from the January Monetary Policy Report (MPR) projection. After a contraction in the fourth quarter of 2025, growth is forecast to have resumed in early 2026. Consumer and government spending are supporting economic activity, while tariffs and trade uncertainty are weighing on exports and business investment. Housing activity declined in the fourth quarter and is held back by slow population growth, economic uncertainty and ongoing affordability issues. The labour market is soft, with subdued employment growth over the past year and job losses in sectors targeted by US tariffs. The unemployment rate remains in the 6½%‑7% range, reflecting both weak hiring and fewer job seekers.”
The Bank’s April forecast projects GDP growth of 1.2% in 2026, rising to 1.6% in 2027 and 1.7% in 2028 as growth in exports and business investment resumes along a lower trajectory. With GDP growing slightly above potential, the current excess supply in the economy is gradually absorbed. While the war in Iran may alter its composition, overall GDP growth is little changed in the updated forecast: Since Canada is a large net exporter of oil, higher oil prices increase national income even as consumers are squeezed by higher gasoline prices.
The Bank’s press release goes on to say that “CPI inflation will likely rise further in April to about 3%. Based on the assumption that oil prices will ease, inflation is forecast to come down to the 2% target early next year and remain around 2% over the projection horizon.
Against this backdrop and taking into account the current projection, Governing Council decided to maintain the policy rate at 2.25%. We are closely monitoring the impact of the conflict in the Middle East and the economy’s response to US tariffs and trade policy uncertainty. Governing Council is looking through the war’s immediate impact on inflation, but will not let higher energy prices become persistent inflation. As the outlook evolves, we stand ready to respond as needed. The Bank is committed to maintaining Canadians’ confidence in price stability through this period of global upheaval.”
WTI crude oil futures jumped more than 5% to above $105 per barrel on Wednesday, amid no signs of a near-term end to the conflict with Iran or the reopening of the Strait of Hormuz. The surge comes as markets weigh the United Arab Emirates’ shock exit from OPEC alongside signs that the conflict involving Iran may persist. Reports that Donald Trump is preparing to extend a blockade on Iranian ports have heightened fears of prolonged supply disruptions, particularly through the critical Strait of Hormuz. Negotiations remain stalled, with both sides entrenched, raising expectations that the standoff could drag on for weeks. Meanwhile, US inventory data showed sharp declines in crude and fuel stockpiles, while exports surged to record highs above 6 million barrels per day, underscoring tightening global supply. Gasoline and refined fuel prices have also spiked, amplifying inflation concerns worldwide as energy markets remain on edge.
The Canadian dollar weakened, and market-driven interest rates rose despite the Bank of Canada’s rate hold. The Fed is expected to follow suit this afternoon, maintaining its policy rate at 3.5% to 3.75%.
Bottom Line
The Bank of Canada has shown its willingness to bolster the Canadian economy amid unprecedented trade uncertainty and a record oil price shock. Ottawa, too, has taken actions to reduce the burden of higher prices on Canadians by temporarily eliminating the excise tax on oil. PM Carney is also working to diversify Canadian trade away from the US.
There will continue to be substantial frictions that limit the geographical diversification of trade sought by Ottawa. The US is Canada’s only neighbour; hence, there is a lack of alternative markets that equal the US in size and scale, and, before Trump, in shared values on free trade.
In his speech before the press conference today, Governor Tiff Macklem suggested that, “if the United States were to impose significant new trade restrictions on Canada, we may need to cut the policy rate further to support economic growth. Alternatively, if oil prices continue to increase, and particularly if they remain elevated, the risk that higher energy prices become ongoing generalized inflation increases. If this starts to happen, monetary policy will have more work to do—there may be a need for consecutive increases in the policy rate.
It is highly unlikely that the Bank of Canada would tighten monetary policy when the housing market is as depressed as it is today.
Latest News Trish Pigott 28 Jan
This morning the Bank of Canada announced no change to the overnight target rate which means no change for our Variable Rate Mortgage holders. I have outlined Dr. Sherry Coopers update below for more detailed insight on our current economic situation.
~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~
Bank of Canada Holds Policy Rate Steady
Today, the Bank of Canada once again held the policy rate steady at 2.25%. This is the bottom of the Bank’s estimate of the neutral overnight rate, where monetary policy is neither expansionary nor contractionary. With inflation hovering just above 2% and core inflation falling to 2.5%, the Governing Council sees the current overnight rate as appropriate, “conditional on the economy evolving broadly in line with the outlook published today. Inflation was 2.1% in 2025, and the Bank expects inflation to stay close to the 2% target over the projection period, with trade-related cost pressures offset by excess supply.”
According to the press release, “Economic growth is projected to be modest in the near term as population growth slows and Canada adjusts to US protectionism. In the projection, consumer spending holds up, and business investment gradually strengthens, with fiscal policy providing some support. The Bank projects growth of 1.1% in 2026 and 1.5% in 2027, broadly in line with the October projection. A key source of uncertainty is the upcoming review of the Canada-US-Mexico Agreement.”
In the United States, economic growth is supported by strong consumption and a surge in AI investment. The Fed stood pat today, but is expected to cut rates three times in the second half of this year. The US Federal Reserve is likely to cut its policy rate by 25 bps to 3.5%-3.75% as President Trump lobbies Chair Jay Powell for more dramatic rate cuts.
Data released yesterday showed that US consumer confidence plummeted in January to the lowest level in 12 years on more pessimistic views from Americans worried about the nation’s economy, inflation and a weakening labour market.
The Conference Board gauge decreased to 84.5 from an upwardly revised 94.2 last month, data released Tuesday showed. The figure was the lowest since May 2014 and fell short of all estimates in a Bloomberg survey of economists.
Bottom Line
The Bank of Canada has shown its willingness to bolster the Canadian economy amid unprecedented trade uncertainty. At the same time, Canada is working hard to establish alternative trade partners. Even the vast Chinese market cannot replace the US in terms of proximity and cost-effectiveness, given the high transport costs. China has stepped up its purchases of Canadian oil to record levels. There is no single market the size of the US market to replace exports of steel and aluminum.
“Employment weakened in the first half of 2025 as sectors hit hard by U.S. tariffs cut production and jobs,” Macklem said. “In recent months, overall employment has risen, led by hiring in services like health care, and slowing population growth is reducing the number of new entrants into the labour market.”
US tariffs have had a significant negative impact on Canadian exports. While the push for trade diversification is welcome, export growth is expected to be modest over the next two years.
“This restructuring, including more diversified trade and a more integrated internal market, will support some recovery in our productive capacity,” Macklem said. “But it will take some time.”
As outlined in its Monetary Policy Report (MPR), the top risk to the outlook is the CUSMA review. The bank highlights that Canada currently has an effective US tariff rate of 5.8%, thanks to the exemptions under the North American trade pact. It warned that an unfavourable outcome to negotiations could make Canadian exports less competitive.
“Faced with weaker demand, exporters would reduce production, investment and hiring,” the report said. “This would spill over into the broader economy, weighing on sectors such as services and putting Canadian GDP on a lower path.”
“Government spending on infrastructure is projected to rise, mainly reflecting commitments in provincial budgets,” the report said. “Additional federal capital transfers will also bolster infrastructure investment.”
In this environment, market-driven interest rates have risen. The 5-year bond yield is once again attempting to break through 3%. The 2-year bond at 2.67% is well above the overnight rate, and the Canadian dollar is rising. Lenders have recently increased fixed mortgage rates, which will be more popular if people generally expect rates to rise.
The key to the outlook is the continuation of CUSMA. We will likely suffer several more months of uncertainty before we know the fate of the trade agreement. In the meantime, PM Carney will continue to encourage trade deals in non-US countries.
Dr. Sherry Cooper
Chief Economist, Dominion Lending Centres
Latest News Trish Pigott 10 Dec
This morning the Bank of Canada made its final announcement of the year and as expected, the Overnight Target Rate which affects the Prime Rate will remain unchanged.
What this means to you as a Home Buyer or Home Owner…if you have a Variable Rate for your mortgage or line of credit, your payment and interest rate will NOT change.
The Overnight Target Rate is what is used by all the banks across the country to set their Prime lending rate. When you have a Variable Rate Mortgage, it is tied to the Prime Rate unlike a Fixed Rate which is set at the start of your mortgage and does not change through the term. Those that choose the Variable Rate, usually do so in order to take advantage of a floating market so that when rates drop, so does the payment and the overall interest costs. Being in a Fixed Rate, it stays the same no matter what the market does after your mortgage completes.
It all depends on comfort and risk tolerance and there is no right or wrong answer to what is right for you. The best thing to do is get the facts and ensure you are working with a professional to get this information and not to solely rely on family, friends and co-workers as their situation will be different than yours so gather the facts and choose what is best for you and your personality. The last thing you want or need is to be kept up at night worrying about mortgage rates so if that’s your personality, a Variable Rate may not be for you.
So for todays announcement, the BoC feels like the economy is not in need of a further cut with unemployment numbers improving last week despite the uncertainty with tariffs and trade policy being a little unstable.
If you would like more detail and to see what DLC’s economist Dr. Sherry Cooper has to say CLICK HERE
There are always lots of questions surrounding this as it can be confusing and overwhelming to understand interest rates and how it all works, so lean on us. It’s our job to be the expert and explain it to you in ways you can understand. Drop a comment, call the office or text me directly.
Have a great Wednesday and enjoy your day ✌☕
Latest News Trish Pigott 29 Oct
Bank of Canada Decreases
Bank of Canada Lowers Policy Rate to 2.25%
Today, the Bank of Canada lowered the overnight policy rate by 25 bps to 2.25% as was widely expected. This is the bottom of the Bank’s estimate of the neutral overnight rate, where monetary policy is neither expansionary nor contractionary. The economy will grow at about a 0.5% pace in Q3, causing the Bank to cut rates again at the final meeting this year on December 10. The easing will then end, but rates will remain relatively subdued until more trade uncertainty is alleviated.
The Fed is widely expected to cut rates by 25 bps this afternoon as well.
Today’s Monetary Policy Report suggests that the significant decline in export growth will persist for some time. Layoffs in trade-dependent sectors have already slowed considerably, especially in Ontario, Quebec, and some softwood lumber businesses in several provinces. The central bank acknowledged that “because US trade policy remains unpredictable and uncertainty is still higher than usual, this projection is subject to a wider-than-normal range of risks.”
“In the United States, economic activity has been strong, supported by the boom in AI investment. At the same time, employment growth has slowed and tariffs have started to push up consumer prices. Growth in the euro area is decelerating due to weaker exports and slowing domestic demand. In China, lower exports to the United States have been offset by higher exports to other countries, but business investment has weakened. Global financial conditions have eased further since July and oil prices have been fairly stable. The Canadian dollar has depreciated slightly against the US dollar.”
“Canada’s economy contracted by 1.6% in the second quarter, reflecting a drop in exports and weak business investment amid heightened uncertainty. Meanwhile, household spending grew at a healthy pace. US trade actions and related uncertainty are having severe effects on targeted sectors, including autos, steel, aluminum, and lumber. As a result, GDP growth is expected to be weak in the second half of the year. Growth will get some support from rising consumer and government spending and residential investment, and then pick up gradually as exports and business investment begin to recover.”
Canada’s labour market remains soft, and job vacancies have declined sharply despite the September improvement in job growth. Job losses continue to mount in trade-impacted sectors, and hiring has been weak across the economy. The unemployment rate remained at 7.1%, well above the US rate of 4.3%. Slower population growth translates into fewer new jobs and less inflation pressue. On a per capita basis, the economy is already in a recession.
The Bank projects GDP will grow by 1.2% in 2025, 1.1% in 2026 and 1.6% in 2027. Quarterly, growth strengthens in 2026 after a weak second half of this year. Excess capacity in the economy is expected to persist and be gradually absorbed.
“CPI inflation was 2.4% in September, slightly higher than the Bank had anticipated. Inflation excluding taxes was 2.9%. The Bank’s preferred measures of core inflation have been sticky around 3%. Expanding the range of indicators to include alternative measures of core inflation and the distribution of price changes among CPI components suggests underlying inflation remains around 2.5%. The Bank expects inflationary pressures to ease in the months ahead and CPI inflation to remain near 2% over the projection horizon”.
“If inflation and economic activity evolve broadly in line with the October projection, the Governing Council sees the current policy rate at about the right level to keep inflation close to 2% while helping the economy through this period of structural adjustment. If the outlook changes, we are prepared to respond. Governing Council will be assessing incoming data carefully relative to the Bank’s forecast.”
Bottom Line
The Bank of Canada has shown its willingness to bolster the Canadian economy amid unprecedented
trade uncertainty. While Canada is working hard to establish alternate trade partners, even China cannot replace the US in terms of proximity and cost-effectiveness, given the huge transport costs. China has stepped up its oil purchases to record levels, but larger oil flows east will require additional pipelines to BC. There is no market the size of the US market to replace exports of steel and aluminum. The US will also suffer from the economic impact of stepping away from the Canada-US-Mexico free trade deal. A renegotiation of the contract is likely to come before the end of next year. As of now, the US is signaling their desire to exit the agreement. We can only hope that cooler heads will prevail.
The auto industry is a case in point. Onshoring non-US auto production would require a 75% increase in US production and the construction of $50 billion in new factories. This would take years and significantly reduce the profitability of US auto companies.
Canada is the US’s number one supplier of steel and aluminum, with its competitively low hydroelectric costs. It will take time for the US to create the capacity to replace aluminum imports from Quebec.
Canada is the number one trading partner for 32 American states, many of which are lobbying Washington to end this CUSMA bashing.
It will take time for Canada to adjust to this new reality, which leads us to conclude that another cut in overnight rates is probable at the next decision date on December 10.
The above report is provided to us by Dr. Sherry Cooper, Chief Economist, Dominion Lending Centres
Latest News Trish Pigott 4 Jun
Todays report and insight is provided by Dr. Sherry Cooper, Chief Economist, Dominion Lending Centres.
As expected, the Bank of Canada held its benchmark interest rate unchanged at 2.75% at today’s meeting, the second consecutive rate hold since the Bank cut overnight rates seven times in the past year. The governing council noted that the unpredictability of the magnitude and duration of tariffs posed downside risks to growth and lifted inflation expectations, warranting caution regarding the continuation of monetary easing.
The gap between the 2.75% overnight policy rate in Canada and the 4.25-4.50% policy rate in the US is historically wide. Another cause of uncertainty is the fiscal response to today’s economic challenges. If the Big Beautiful Bill, now under consideration in the Senate, survives, the US is slated to run unprecedented budget deficits. The Congressional Budget Office estimates it would add roughly US$4 trillion to the already burgeoning federal government’s red ink. This has caused a year-to-date rise in longer-term bond yields, steepening the yield curve.
Uncertainty remains high, and the US President just doubled the tariff on steel and aluminum to 50%, which could halt Canadian metals exports to the US. Last week’s release of the first quarter GDP report at 2.2% annualized growth was stronger than expected as exports and inventories surged before the tariffs. Final domestic demand in Canada was flat. More recent data showed considerable weakness, especially in labour and housing markets. Consumer spending has also slowed sharply.
In today’s press conference opening comments, Governor Macklem said, “The extreme financial turmoil we saw in April has moderated, and stock markets have recovered their losses. However, the outcomes of the trade negotiations are highly uncertain. Tariffs are well above their levels at the beginning of 2025, and new trade actions are still being threatened. The recent further increases in US tariffs on steel and aluminum underline the unpredictability of US trade policy.”
“So far, the US economy has proven resilient. Imports were strong as businesses tried to get ahead of tariffs, and that pulled down first-quarter US GDP. But domestic demand remained relatively strong. Early indicators for the second quarter suggest a rebound in growth as imports fall back and domestic demand continues to expand.
The flip side of the strength in US imports was a surge in Canadian exports. This boosted first-quarter GDP growth in Canada, which came in at 2.2%, slightly stronger than the Bank had forecast.
The labour market has weakened, with job losses concentrated in trade-intensive sectors. The unemployment rate rose to 6.9% in April. So far, employment has held up across sectors less exposed to trade. However, businesses generally tell the central bank they plan to scale back hiring.
The pull forward in exports and inventory accumulation in the first quarter borrows economic strength from the future, so the second quarter is expected to be much weaker. Canadian families and businesses’ spending has shown some resilience in the face of US tariffs and heightened uncertainty. But they will likely remain cautious, suggesting domestic spending will remain subdued.
Inflation excluding taxes was 2.3% in April, slightly more substantial than the Bank had expected and up from 2.1% in March. The Bank’s preferred measures of core inflation and other measures of underlying inflation moved up in April. There is some unusual volatility in inflation, but these measures suggest underlying inflation could be firmer than we thought. Higher core inflation can be partly attributed to higher goods prices, including food, and may reflect the effects of trade disruption. Many businesses report higher costs for finding alternative suppliers and developing new markets. The Bank will be closely watching measures of underlying inflation to gauge how inflationary pressures are evolving.
The Bank is also monitoring inflation expectations closely. In April, we reported that consumers and businesses expected prices to rise due to tariffs, while longer-term inflation expectations remained well anchored. Recent surveys continue to show consumers bracing for higher prices, and many businesses say they intend to pass on tariff costs.
Governing Council will continue to assess the timing and strength of the downward pressure on inflation from a weaker economy and the upward pressure on inflation from higher costs.
At this decision, there was a consensus to hold the policy unchanged as we gain more information. The BoC also discussed the path ahead for the policy interest rate. Here, there was more diversity of views. On balance, members thought there could be a need for a reduction in the policy rate if the economy weakens in the face of continued US tariffs and uncertainty, and cost pressures on inflation are contained.
Bottom line;
We expect the Canadian economy to post a small negative reading (-0.5%) in both Q2 and Q3, bringing growth for the year to 1.2%, just one tick above the recently released OECD forecast for Canada. The next Governing Council decision date is July 30, which will give the Bank time to assess the underlying momentum in inflation and the dampening effect of tariffs on economic activity.
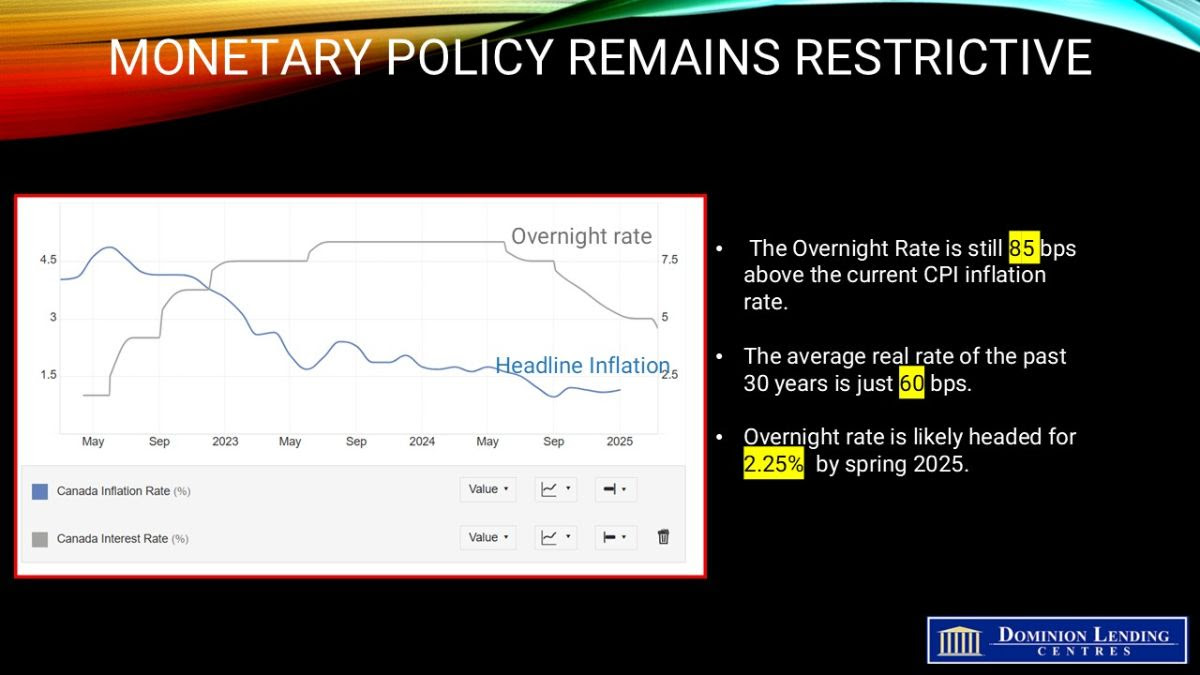
If inflation slows over the next couple of months—we get two CPI releases and two jobs reports before the next meeting—and the economy slows in Q2 and Q3 as widely expected, the Bank will likely cut rates two more times this year, bringing the overnight rate down to 2.25%.
Latest News Trish Pigott 12 Mar
|
||||||||||||
|