Mortgage Rates Could Rise. Is your mortgage ready?

Latest News Trish Pigott 26 Oct

Recent economic forecasts suggest the Bank of Canada may begin increasing interest rates sooner than originally expected, possibly as early as October 28, with further increases in 2027. While nothing has been confirmed, this means we may not see the lower mortgage rates many homeowners were hoping for.

Here’s what you should know:

  • Variable rates: Could increase over the coming months if the Bank of Canada raises its rate.

  • Fixed rates: Have remained relatively stable recently, but could still fluctuate based on the economy and bond markets.

  • Mortgage renewals: If your mortgage is coming up for renewal in the next 6 – 12 months, now is a good time to review your options.

Example of How Payments Can Be Affected

Canadian Variable Mortgage Payment Comparison

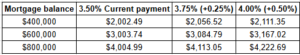
Below is a comparison showing how a 0.25% or 0.50% increase in variable mortgage rates could affect homeowners with mortgage balances of $400,000, $600,000 and $800,000.

Assumptions: Starting rate of 3.50%, 25 years remaining, monthly payments, and semi-annual compounding. Calculations assume payments are adjusted immediately to maintain the 25-year amortization.
How much more would homeowners pay?

$400,000 mortgage

+0.25% rate increase

$54.03 more per month

+0.50% rate increase

$108.85 more per month

$600,000 mortgage

+0.25% rate increase

$81.05 more per month

+0.50% rate increase

$163.28 more per month

$800,000 mortgage

+0.25% rate increase

$108.06 more per month

+0.50% rate increase

$217.71 more per month

Reminder: Adjustable-rate mortgages generally change payments when rates change. Fixed-payment variable mortgages may instead keep payments unchanged while more goes toward interest and less toward principal, potentially extending the amortization.

What Should Home Owners and Home Buyers Prepare For?

Variable mortgage holders: Prepare for the possibility of a 0.50-percentage-point increase over the next several months. Review affordability and payment adjustments now rather than waiting for the Bank of Canada announcement.

Fixed-rate borrowers: Continue comparing three-year and five-year fixed options. There is currently insufficient evidence to conclude that fixed rates will increase significantly in the immediate future.

Homeowners Renewing in 2027: Budget conservatively. The possibility of further rate reductions has weakened, but the evidence does not yet justify substantially increasing our five-year mortgage-rate projections.

The next announcement is October 28, 2026, when the Bank of Canada will announce its interest-rate decision and release updated economic projections.

Reminder: if there is a change, it will be to the Overnight Target Rate which affects the Prime Rate not, Fixed Rates. Fixed Rates could change if the bond market and the dollar are affected so lock in a rate now if you are on the fence or looking at a change to your current mortgage. When in doubt, contact us to lock in your rate.

Our advice? Don’t try to time the market. Time your life and your budget. The lowest rate isn’t always the best mortgage. Choosing the right term, payment structure and flexibility for your personal situation is what matters most.
BOOK YOUR FREE 15-MINUTE MORTGAGE REVIEW

Buyers Secret ~ Purchase Plus Improvement ~ Finance your Renovations

Home Tips Trish Pigott 31 Aug

PURCHASE PLUS IMPROVEMENTS

Buy the home. Make it yours. Finance the improvements.

Found the right home… but it needs a little work?

A Purchase Plus Improvements Mortgage may allow you to include the cost of eligible renovations in your mortgage when purchasing your new home.

Instead of passing on a property because the kitchen is dated, the floors need replacing or the bathroom needs an update, you may be able to purchase now, renovate after possession and finance both together.


HOW DOES IT WORK?

1. Find Your Home
Purchase a property that has potential but needs improvements or updating.

2. Decide What You Want to Improve
Identify the renovations you would like to complete and obtain written quotes or estimates before your mortgage is finalized.

3. We Structure the Financing
The cost of the approved improvements is incorporated into your mortgage financing, subject to lender and mortgage insurer approval and the property’s supported “as-improved” value.

4. Complete Your Purchase
Your home purchase closes and you take possession. The renovation portion of the mortgage is generally held back by the lender until the approved work is completed.

5. Complete the Renovations
Complete the improvements within the timeframe required by your lender. You may need access to your own funds or credit to pay contractors and suppliers while the work is being completed.

6. Verification & Release of Funds
Once the approved work is complete, the lender verifies the renovations. This may involve receipts, invoices, photographs and/or an inspection. Once approved, the renovation holdback is released according to the lender’s process.


WHAT TYPES OF IMPROVEMENTS MAY QUALIFY?

✓ Kitchen renovations
✓ Bathroom renovations
✓ New flooring
✓ Windows and doors
✓ Roofing
✓ Plumbing or electrical upgrades
✓ Basement finishing
✓ Heating and energy-efficiency improvements
✓ Other permanent improvements that add value to the home

Generally not eligible: furniture, electronics and other movable personal items. Eligibility ultimately depends on the lender and mortgage insurer.


QUICK EXAMPLE

Purchase Price: $650,000
Approved Improvements: $40,000
Purchase + Improvements: $690,000

Rather than purchasing the home and trying to arrange separate renovation financing afterward, we can explore whether the $40,000 of improvements can be incorporated into the mortgage financing from the beginning.

Your required down payment and maximum mortgage are calculated according to applicable mortgage-insurance and lender requirements.


IMPORTANT THINGS TO KNOW

  • You must qualify for the total mortgage, including the approved improvements.
  • Renovation quotes are generally required before final mortgage approval.
  • The property’s as-improved value must support the financing.
  • The renovation funds are typically not provided to you as cash on closing day.
  • You should have a plan to cover renovation expenses until the lender releases the holdback.
  • Renovations must be completed within the lender’s required timeframe.
  • The lender will require verification that the approved work has been completed.
  • Program guidelines vary between lenders and Canada’s three mortgage insurers: CMHC, Sagen and Canada Guaranty.

FOR REALTORS

Don’t automatically rule out the dated house.

If your buyer loves the location, layout and property but doesn’t love the finishes, talk to us before writing the offer.

We can review the buyer’s qualification and determine whether a Purchase Plus Improvements strategy could allow them to buy the property and finance eligible renovations at the same time.

BEFORE YOU WRITE THE OFFER ~ CALL US.

PRIMEX MORTGAGES
Trish Pigott | Owner / Mortgage Broker
Guiding Canadians Home.

Purchase Plus Improvements programs are subject to borrower qualification, property valuation, lender guidelines and mortgage insurer approval.

Program requirements may change. Contact Primex Mortgages for current eligibility and financing details.

Down Payments Required When Purchasing a Home

Mortgage Tips Trish Pigott 26 Jun

Her is a little insight to minimum down payment requirements and the two types of mortgages that are available for home buyers.

High ratio mortgages are when you have less than 20% of the purchase price for down payment available.  Your mortgage is required to be insured by one of Canada’s three Mortgage insurers.  CMHC, Sagen or Canada Guaranty.  The insurance premiums are also scaled based on your down payment.  Mortgage insurance will apply and be added to the total mortgage amount. This is a Canadian requirement with all banks.  Here is a link to my Purchase Calculator so you can see what the cost is based on how much you have for down payment and insurance is required.

Conventional mortgages are when you have more than 20% of the purchase price for down payment. The 20% is calculated based on the total purchase price which allows you to avoid having to pay for mortgage insurance. For any purchase price over $1.5 million, you are required to have 20% down or more.

Rental properties also require a minimum of 20% down payment.

Down payment funds must be in your name for a minimum of 90 days and we require bank statements or investment statements confirming the funds are in your name.

If they are being gifted by an immediate family member, a gift letter is required for you and your family member to sign confirming that the gift does not require repayment, and the funds must be deposited into your bank account a minimum of 15 days prior to completion of the purchase. We will also require a printout of your bank statement showing the gifted funds deposited. The amount deposited must match the gift letter to the penny.

Interest rate rates are also set based on their down payment. For high ratio mortgages, there are often lower interest rates compared to conventional mortgages. Don’t be alarmed when you see different rates being offered and also don’t be fooled looking at advertisements online with rock-bottom interest rate rates and think that they apply to conventional mortgages.

The best way to navigate this is to contact us directly so we can walk you through the process step-by-step on how you will be affected with your upcoming purchase and what your minimum down payment requirements look like.

Easy Guide to Improving your Credit Score in Canada

Mortgage Tips Trish Pigott 7 May

For Existing Homeowners and Future Homeowners

What Is a Credit Score?

Your credit score is like a “financial report card.” It helps banks and lenders decide:

* If they will lend you money
* What interest rate you qualify for
* How much you can borrow

In Canada, credit scores usually range from:

**300–559** = Poor
**560–659** = Fair
**660–724** = Good
**725–759** = Very Good
**760–900** = Excellent

The higher your score, the better your mortgage and financing options may be.

The 5 Biggest Things That Affect Your Credit Score

1. Payment History (Most Important)

This means paying your bills on time.

Examples:

* Credit cards
* Loans
* Car payments
* Mortgage payments
* Cell phone bills
* Lines of credit

Best Practice:

✅ Always make payments on time
✅ Set up automatic payments if possible
✅ At minimum, make the minimum payment before the due date

What Hurts Your Score:

❌ Missed payments
❌ Late payments
❌ Collections or unpaid debts
❌ NSF or bounced payments

2. Credit Utilization (How Much You Owe)

This means how much of your available credit you are using.

Example:

If your credit card limit is $10,000:

* Using $2,000 = Great
* Using $8,000 = Too high

Best Practice:

✅ Keep balances below 30% of your limits
✅ Lower is even better (under 10% is excellent)

What Hurts Your Score:

❌ Maxed out credit cards
❌ Carrying large balances month after month

3. Length of Credit History

The longer you responsibly use credit, the better.

Best Practice:

✅ Keep older accounts open if possible
✅ Use older cards occasionally to keep them active

What Hurts Your Score:

❌ Closing old credit cards
❌ Constantly opening new accounts

4. Credit Checks (Inquiries)

Every time you apply for financing, lenders may check your credit.

Best Practice:

✅ Only apply for credit when needed
✅ Work with one trusted mortgage broker instead of multiple lenders separately

What Hurts Your Score:

❌ Applying for many credit cards or loans quickly
❌ Multiple hard credit checks in a short time

5. Types of Credit

Having different kinds of credit can help.

Examples:

* Credit cards
* Car loans
* Mortgage
* Line of credit

Best Practice:

✅ Manage different credit types responsibly

What Hurts Your Score:

❌ Too many payday loans
❌ Too much unsecured debt

Step-by-Step Plan to Improve Your Credit Score

Step 1: Check Your Credit Report

Review your Equifax Canada report for:

* Incorrect balances
* Accounts that are not yours
* Old debts that should be removed
* Incorrect late payments

You can check your report here:

Equifax Canada CLICK HERE

Step 2: Make Every Payment On Time

This is the fastest way to build credit over time.

Helpful Tips:

* Use calendar reminders
* Set up automatic minimum payments
* Pay bills a few days early

Step 3: Lower Credit Card Balances

Aim to keep balances:

* Below 30% of the limit
* Ideally below 10%

Example:

If your limit is $5,000:

* Try to stay below $1,500
* Under $500 is even better

Step 4: Avoid Applying for Too Much Credit

Before applying for:

* Credit cards
* Car loans
* Financing

Ask yourself:

“Do I really need this right now?”

Too many applications can temporarily lower your score.

Step 5: Keep Older Accounts Open

Even if you do not use a card often:

* Small purchases every few months can help
* Pay them off right away

Step 6: Create a Monthly Budget

Good budgeting helps prevent:

* Missed payments
* High balances
* Debt stress

Focus on:

✅ Reducing debt
✅ Paying bills early
✅ Building savings

Credit Tips for Homeowners

Existing Homeowners

Best Things You Can Do:

✅ Make mortgage payments on time
✅ Avoid taking on unnecessary debt
✅ Keep HELOC balances manageable
✅ Avoid refinancing too often without a plan

Be Careful Of:

❌ Missing mortgage payments
❌ Using home equity for ongoing spending
❌ Taking on large monthly obligations

New Homeowners

Important First-Year Tips:

✅ Keep emergency savings
✅ Avoid financing furniture immediately after possession
✅ Do not open multiple new credit accounts after buying a home
✅ Continue paying all bills on time

Many people hurt their credit after buying by:

❌ Maxing out cards for renovations or furniture
❌ Missing payments during the move
❌ Taking on too many monthly payments

What NEGATIVELY Impacts Your Equifax Credit Score

These are some of the biggest credit score mistakes:

❌ Late payments
❌ Missed mortgage payments
❌ Maxed-out credit cards
❌ Collections
❌ Bankruptcy or consumer proposals
❌ Multiple credit applications
❌ Payday loans
❌ Closing old credit accounts
❌ High debt balances
❌ Bounced payments
❌ Unpaid phone bills or utilities

How Fast Can Your Credit Score Improve?

Everyone is different, but many people start seeing improvements within:

**30–90 days** after lowering balances
**3–6 months** of on-time payments
**6–24 months** for major rebuilding

Credit scores improve with consistency over time.

How to Correct Errors on Your Equifax Report

Mistakes on a credit report can happen.

Examples include:

* Incorrect late payments
* Wrong balances
* Accounts that are not yours
* Identity theft issues

Steps to Dispute Errors with Equifax Canada

Step 1: Gather Documents

Examples:

* Bank statements
* Payment confirmations
* Letters from lenders
* Identification

Step 2: Contact Equifax Canada

Online:

Equifax Canada Dispute Centre CLICK HERE
Phone:
1-800-465-7166

Mail:
Equifax Canada Co.
National Consumer Relations
P.O. Box 190
Montreal, Quebec H1S 2Z2

Step 3: Wait for Investigation

Equifax will contact the lender or creditor to verify the information.

Typical timelines:

* Investigations often take **5–30 days**
* Updates to scores may appear within **30–60 days**
* Sometimes faster depending on the lender

Final Credit Success Tips

To Build Strong Credit Over Time:

✅ Pay everything on time
✅ Keep balances low
✅ Avoid unnecessary debt
✅ Review your credit regularly
✅ Keep older accounts active
✅ Create a monthly budget
✅ Be patient and consistent

Small positive habits each month can create major improvements over time.

Need Help Understanding Your Credit or Mortgage Options?

Whether you are:

* Buying your first home
* Renewing your mortgage
* Refinancing debt
* Improving your credit
* Planning for future homeownership

Schedule a credit review to discuss over the phone, click here to BOOK A CALL

Why are rates online so much lower than what you are being offered?

Mortgage Tips Trish Pigott 4 Feb

Mortgage rates are not created equal and either are buyers and homeowners. There’s a lot that goes into the difference between mortgage rates and what you are eligible for. Banks and rate sites offer the rock bottom rates like loss leaders to just get you to contact them. Once they determine your situation they will tell you that can either get that rock bottom rate or you don’t qualify and not necessarily because you have bad credit or not enough income, your property value and equity matters more.

Let’s start with a bit of a breakdown.

🛡️ Insured Mortgages (Commonly known as High Ratio)

  • Typically used by first-time buyers
  • Down payment: Less than 20%
  • Mortgage insurance: Required (CMHC, Sagen, or Canada Guaranty)
  • Who pays the insurance? The buyer (added to the mortgage amount)
  • Home price limit: Up to $1.5 million (with minimum down payment rules)
  • Amortization can be up to 30 years for First Time Buyers only
  • Interest rates: Usually the lowest available
  • Available to purchasers whether first time home buyer repeat buyers
  • Why? Lenders are protected by the insurer in the event you default on payment, so they offer better rates as you are lower risk.

Good to know:
Even though you pay for the insurance, you benefit from lower rates and easier qualification.

🏠 Insurable Mortgages

  • The “best of both worlds” option
  • Down payment: 20% or more
  • Mortgage insurance: Not paid by the buyer, but the mortgage meets insurance guidelines
  • Home price limit: Typically under $1 million
  • Amortization: Up to 25 years maximum
  • Interest rates: Very competitive — often close to insured rates
  • Available to purchasers and those with mortgages up for renewal that do not want to make any changes and just move lenders for better rates. Property value must be under $1M.
  • Why? The mortgage can be insured by the lender if they choose, reducing their risk

Good to know:
Many buyers don’t realize this option exists — it can mean better pricing without paying insurance.  When you have more than 35% down payment or equity, you get rock bottom rates and do not have to pay the insurance but receive the same benefits.

💼 Conventional Mortgages (Commonly known as Uninsured)

  • More flexibility, fewer restrictions
  • Down payment: 20% or more
  • Mortgage insurance: Not required
  • Home price: No maximum
  • Amortization: Can be 30 years
  • Interest rates: Usually slightly higher
  • Available to all purchasers with more than 20% down payment, refinance clients or mortgage renewals when property value is over $1M
  • Why? The lender takes on more risk as it’s not insured on the back end, so pricing reflects that

Good to know:
This option is common for higher-value homes, rental properties, or buyers wanting longer amortizations, refinances and debt consolidations.

✨ Quick Comparison

  • Lower than 20% down? → Insured
  • 20%+ down & under $1M? → Possibly Insurable
  • 20%+ down & more flexibility needed? → Conventional

So in summary, don’t get caught up in the rates you see advertised as mortgages are not a one size fits all and not all mortgage rates are offered equally.  When in doubt reach out and we an quickly tell you what bucket you fall into.  Click here to  BOOK A CALL we’d love to help you!

Shave 10 Years off Your Mortgage

Mortgage Tips Trish Pigott 13 Jun

🏡 Here’s a practical and effective plan for Canadians to shave 10 years off the life of their mortgage — without dramatically changing your lifestyle. This plan combines strategies to reduce interest and maximize your payments strategically.

🔹 1. Start with a Mortgage Check-Up
Review your amortization and interest rate. If it’s over 25 years or your rate is above 5%, you’re likely paying too much in interest. This is a free service we provide for all new and existing mortgage clients.

We will help you determine if a refinance or early renewal could save you thousands and reduce amortization.

🔹 2. Accelerate Your Payment Frequency
Switch from monthly to bi-weekly accelerated payments.

This results in 1 extra monthly payment per year.

Example: On a $500,000 mortgage at 5.5%, this can cut over 3 years off your term.

🔹 3. Increase Your Payments
Use your lender’s prepayment privileges to increase your regular payment by 10–20%.

Even an extra $100/month can shave years off your mortgage.

🔹 4. Make Lump Sum Payments Annually
Apply bonuses, tax refunds, or side income toward your mortgage as lump sum payments.

Most lenders allow up to 15–20% of your original mortgage as a lump sum annually without penalty.

🔹 5. Round Up Your Payments
If your payment is $1,184, round it to $1,200 or $1,250. You won’t feel a big difference month to month, but it can cut interest and time drastically.

🔹 6. Refinance Strategically
Refinance to a lower rate or shorter term if rates drop or your financial situation improves.

Consider refinancing to a 15- or 20-year term if you can handle slightly higher payments.

🔹 7. Avoid Mortgage Penalties Smartly
Time prepayments for your mortgage anniversary date.

Know your lender’s rules on lump sums, increases, and penalties to avoid surprises.

🔹 8. Use a Mortgage Prepayment Calculator
We do this for you with your mortgage check-up and will help you to visualize how extra payments reduce your amortization.

🔹 9. Automate Extra Payments
Automate your bi-weekly accelerated payments and any extra amount to make it consistent and effortless.

🔹 10. Review and Adjust Annually
Review your mortgage annually with us. Markets and rates change and so do your circumstances. Don’t assume this should only be done at the end of your term.

Re-evaluate your goals and income to determine if you can boost payments further.

~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~~

💡 Example: $500,000 Mortgage @ 5.5% Interest, 25-Year Term
Bi-weekly accelerated payments: Save ~3 years

$200/month extra: Save ~4–5 more years

$5,000 lump sum yearly: Save 2–3 more years
➡ Result: Mortgage paid off in ~15 years instead of 25

🚀 Final Tip:
Every extra dollar goes toward the principal early in your mortgage. The first 5 years are the most powerful time to make additional payments and shorten your mortgage dramatically. So if you have not had a mortgage check-up lately, book in with us, we will help you. It takes less effort than you think to become mortgage free.

5 Tips for Grads for Future Financial Success

Mortgage Tips Trish Pigott 12 Jun

Here are 5 essential financial tips every graduate should know before leaving school — practical, Canadian-focused, and geared toward long-term success:

🎓 1. Credit Scores Matter More Than You Think
Your credit score affects your ability to get a mortgage, rent an apartment, buy a car, or even get hired.

Start by getting a student credit card, using it responsibly, and always paying it off on time.

Monitor your score for free through your bank or apps like Borrowell or Credit Karma.

💳 2. Avoid Lifestyle Inflation
It’s tempting to upgrade your lifestyle with your first “real” paycheck, but avoid overspending.

Stick to a budget and build a cushion before splurging.

Follow the 50/30/20 rule: 50% needs, 30% wants, 20% savings/debt repayment.

💸 3. Student Loans Don’t Disappear
Federal student loans in Canada have a 6-month grace period, but interest starts accruing immediately.

Make a plan to start repaying early if possible to reduce your total cost.

Use government repayment assistance if your income is low after graduation.

🏦 4. Start Saving — Even If It’s Just $25/month
Open a TFSA (Tax-Free Savings Account) or RRSP and start small.

Automatic transfers into savings build great habits and grow over time.

Compound interest is powerful — the earlier you start, the easier it gets.

📚 5. Financial Literacy = Financial Freedom
Learn about investing, budgeting, and taxes — it’s not as scary as it sounds.

Understanding your money = more control over your future.

If you would like to book a free 15 minute call to ensure you get on the right track, contact us and we will get you started.

Tips to Pay off Your Mortgage Faster

Mortgage Tips Trish Pigott 25 Sep

Paying off your mortgage faster in Canada can save you a significant amount in interest and help you become debt-free sooner. Here are the top 5 tips to achieve that:
 
1. Make Biweekly Payments
 
Instead of making one monthly payment, switch to biweekly payments. This results in 26 half-payments, which equals 13 full payments each year instead of 12. That extra payment can significantly reduce the interest over time.
 
2. Pay Extra Toward the Principal
 
Whenever you can, make extra payments that go directly toward the principal balance. Even small additional amounts such as $100 can have a huge impact, especially if done consistently over the life of the loan. Usually you can make lump sum payments up to 15-20% of your original mortgage amount without penalty.
 
3. Refinance to a Lower Interest Rate
 
Refinancing from a higher rate to a lower rate can significantly reduce the interest paid over time. Although you may have to pay a penalty to change the mortgage, often you will save and pay less interest in the long run.
 
4. Round Up Your Mortgage Payment
 
Round up your regular mortgage payment to the next $100. For instance, if your bi-weekly payment is $1321, round it up to $1400. Chances are you won’t even remember you did it a month later and that extra amount goes straight to principal.
 
5. Shorten the Amortization Period
 
When your mortgage renews, try to shorten the length of your amortization period (e.g., from 25 years to 23 or even 20 years) can dramatically lower the total interest paid and get you mortgage-free faster.
 
By following these strategies, you can minimize interest and accelerate the path to being mortgage free faster!

The True Cost of Downsizing

General Trish Pigott 10 Oct

Many Canadians consider downsizing during their retirement years. Once their children have left the nest, the choice seems obvious: relocate to a smaller residence or a more affordable town and capitalize on the price difference. For many retirees, the funds from the sale of their home can significantly impact their overall lifestyle and financial well-being.

However, there are downsides of downsizing you should be aware of before you call your Realtor.

Downsizing in British Columbia: A Cost Analysis

The cost of moving is probably one of the most significant downsides to downsizing. To give you an idea of the figures involved, we conducted a cost analysis for a typical downsizing scenario using an example of selling a home in Vancouver for $1,000,000 and buying a condo for $700,000.

This would free up $300,000 in equity while moving you into a smaller home. According to Stats Canada, you need a nest egg of about $450,000 to retire comfortably in Canada. The money from the sale of your house could have a meaningful impact on your retirement finances. But how much of that chunk will you get to keep to boost your nest egg? Below is an estimated list of cost considerations when choosing to downsize:

Fees Downsizing CHIP Reverse Mortgage
Real estate fees (average 7% selling price on the first $100k of the home price, and average 1% on the remaining total) $34,000 N/A
Legal Fees $1,200-$2,400 $300-$600
Land Transfer Tax (Varies depending on province and city) $12,000 N/A
Moving expenses (packing supplies, moving service, garbage removal, etc.) $3,000-$6,500 N/A
Furnishing and upgrades $8,000-$25,000 N/A
Home appraisal $500 $300-$600
Closing fee $500-$2,250 $1,795-$2,995
Total $59,200-$82,650 $2,395-$4,195


As you can see, downsizing could cost you between $59,200-$82,650.

If you live in a big city like Vancouver, $300,000 of equity could shrink to just $217,350* after considering these downsizing costs. However, these costs are not the only adverse effects of downsizing to consider.

*Based on $300,000 of equity minus $82,650 (the highest downsizing cost).

The Downsizing Dilemma 

Many Canadians underestimate the financial and emotional costs of downsizing, overlooking various aspects:

  • Home Improvements: Before selling, homes often need upgrades, from simple fixes to major renovations like kitchens or roofs. Also, many invest in staging their homes.
  • Belonging Decisions: Downsizing means deciding which possessions to keep due to space constraints, often leading to emotional challenges and storage expenses.
  • Leaving Family Homes: Leaving a home that carries so many joyful memories, especially if someone is widowed, can be challenging. Relocating might disconnect you from communities and loved ones.

An Alternative to Downsizing in Canada: The CHIP Reverse Mortgage 

The CHIP Reverse Mortgage by HomeEquity Bank can be the ideal alternative to downsizing. Unlock up to 55% of your home’s equity in tax-free cash while staying in your beloved home without leaving the neighbourhood you love. This money improves your retirement finances and can be used to renovate and retrofit the home for accessibility and livability as you age. With no required monthly mortgage payments, the CHIP Reverse Mortgage is becoming a popular solution.

If you have any questions or are curious about what would be best for you, don’t hesitate to contact us at 604-552-6190! Or you can CLICK HERE to book a call with Trish!

Trish & The Primex Team

Understanding Mortgage Rates

Mortgage Tips Trish Pigott 16 Aug

While not the only factor to consider when choosing a mortgage, interest rates remain one of the more prominent decision criteria with any mortgage product. Understanding how mortgage rates are determined and the differences between your typical fixed-rate and variable-rate options can help you make the best decision to suit your needs.

How Rates Are Determined

The chartered banks set the prime-lending rate (the rate they offer their best customers). They base their decisions on the Bank of Canada’s overnight rate because it influences their own borrowing. Approximately eight times per year, the Bank of Canada makes rate announcements that could affect your mortgage as variable mortgage rates and lines of credit move in conjunction with the prime lending rate. When it comes to fixed-rate mortgages, banks use Government of Canada bonds. In the bond market, interest rates can fluctuate more often and provide clues on where fixed mortgage rates will go.

Simply put, a variable rate is based on the current Prime Rate and can fluctuate depending on the market. A fixed rate is typically tied to the world economy, whereas a variable rate is linked to the Canadian economy. When the economy is stable, variable rates will remain low to stimulate buying.

Fixed-Rate vs. Variable-Rate

Fixed-Rate Mortgage

First-time homebuyers and experienced homebuyers typically love the stability of a fixed rate when just entering the mortgage space.

The pros of this type of mortgage are that your payments don’t change throughout the life of the term. However, should the Prime Rate drop, you won’t be able to take advantage of potential interest savings.

Variable-Rate Mortgage

As mentioned, variable-rate mortgages are based on the Prime Rate in Canada. This means the interest you pay on your mortgage could go up or down, depending on the Prime. When considering a variable-rate mortgage, some individuals will set standard payments (based on the same mortgage at a fixed rate). This means that should Prime drop and interest rates lower, they would pay more to the principal instead of paying interest.

If the rates go up, they pay more interest instead of direct to the principal loan.

Other variable-rate mortgage holders will allow their payments to drop with Prime Rate decreases or increases should the rate go up. Depending on your income and financial stability, this could be a great option to take advantage of market fluctuations.

Getting into the real estate market? Let’s get you pre-approved! That way you can be confident making an offer on your dream home.

Let’s chat!

604-552-6190

support@primexmortgages.com

Trish & The Primex Team