How to Create a Monthly Budget

General Trish Pigott 26 Jul

Creating a monthly budget is the quickest way to take control of your finances and understand where your money is going. You can then review your monthly spending habits to get a snapshot of your incoming and outgoing transactions, and determine areas for improvement.

Step 1: Calculate Your Income

The very first step to creating a budget is determining your income. It is important to know what your net income is each month, so that you know what you have available to spend.

Step 2: Track Your Spending

Once you have determined your income, you will want to take a look at your spending. Reviewing and categorizing all your monthly bills can help you break things down. To start, list out your fixed expenses – these are things like car payments, loans, rent or mortgage costs that do not change on a monthly basis. Next, take a look at your variable expenses – things like groceries, gas, entertainment, etc., and determine your average spend. This is typically the area where people are able to cut back.

Step 3: Set Realistic Goals

Realistic goals are vital for long-lasting financial health. It is important to determine what you cannot live without and where you can cut costs or scale back on spending. Ideally, when it comes to your monthly budget, you want to consider the 50/30/20 rule, which applies the following:

  • 50% of your spending is for NEEDS such as rent or mortgage payments, car payments, utilities and groceries
  • 30% of your income goes to WANTS such as shopping, vacations, streaming services, etc.
  • 20% of your income goes to SAVINGS OR DEBT such as emergency funds, retirement, child’s education and/or credit card payments

Step 4: Make a Plan

Once you have your goals set, you can now make a plan to tackle your financial position and ensure a healthy cashflow each month. For some, setting realistic spending limits for each category works well. For others, taking a look at their expense list and re-prioritizing can free up funds.

Step 5: Adjust Your Spending

Now you can take a look at adjusting your spending to ensure you remain on budget. This is also a great time to review your fixed expenses. Perhaps you can save money by getting a better interest rate on your mortgage or changing your payment schedule for your loan.

Step 6: Stay on Track With Your Budget

Lastly, once you’ve tracked all your spending and income, and determined a monthly budget, you will want to stay on track. Tracking your budget on a monthly basis is important to catch any changes in your spending habits. It is also a good idea to conduct an annual review and take into account any increase in expenses or wages that may require shifts in your overall plan.

Remember! A healthy, well-thought-out budget is key to financial freedom and comfort.
Financial Advice That Never Gets Old

General Trish Pigott 19 Jul

Looking for financial advice on your personal finances? Here are five timeless recommendations:

1. Start Investing Small and Early

Only around 5% of Canadians under 25 have a TFSA (Tax Free Savings Account), which means 95% have already missed out on seven years of compounded returns. Starting small could be as little as $100 month, and starting early means now! Invest what you can and don’t ever think that any amount is too small.

Investing $100 month at 5% for 47 years (age 18 to 65) will give you $68,754 more than someone who did the same starting from age 25.

2. Make More OR Spend Less?

Our financial advice is to do both, but there are limits on how much income you can generate and cutting back on expenses has a bigger impact on your bottom line. If you’re lucky, you may find some expenses you could easily do without, like that lightly used gym membership or seldom watched 200-channel cable package.

A part-time job or side hustle isn’t a bad idea, but you will spend more time working and less time enjoying life. Don’t forget that any extra income is fully taxable — you might need to earn $10 in order to get the same result as a $7 spending cut.

3. Re-Evaluate Your Wants and Needs

A 1200 square foot bungalow was the standard for most families in the early 1970’s. These days, houses are now over 2000 square feet on average and come with plenty of high-end finishes. Being able to live comfortably later in life will come from making smart spending decisions.

4. Understand Credit and Debt

131 months! That’s how long it takes to pay off a $1000 credit balance paying the minimum amount — Plus it will cost you almost $1000 more in interest charges! Many people carry a credit card balance and are blissfully unaware of just how much it is costing them each month.

The key is to be knowledgeable about your debt. Track what you owe and how much that debt is costing you. For example, refinance your mortgage or draw on home equity to pay off higher interest loans and credit cards.

5. Get Financially Literate

Managing your money has become more difficult as we have a lot more spending, saving, and investing options. But, we also have access to a lot more information and tools to help us. For example, diving into the real impact of those investment fees on your mutual funds (it’s a lot!) can easily be investigated online in just a few minutes.

Bank of Canada Increases Prime Rate Again

General Trish Pigott 14 Jul

Yesterday the Bank of Canada surprised all economists and financial industry professionals by an increase to the overnight target rate of 1.00%. This was in response to the continued rise of inflation across the country.  Most were only predicting an increase of 0.75%, so the 1.00% was higher than expected.

Here’s what you need to know about yesterday’s increase:

  • The Prime rate pertaining to mortgages and lines of credits will increase to 4.70%; most will be today or at the first of the month
  • Your discount off of your mortgage will still apply, meaning that if you have a mortgage at Prime -0.90%, your new rate would be 3.80% (4.70% – 0.90% = 3.80%)
  • For every $100,000 in mortgage amount, it will cost you an extra $55 per month
  • A Variable Rate or Adjustable Rate will determine if your payment changes when Prime does; call our office if you need help to clarify that
  • The Bank of Canada indicated that they are predicting we will see additional increases by the end of the year in order to combat inflation.  Until Canadians slow down on spending, whether it’s cars, houses, entertainment or shopping, the Bank of Canada will do what it can to curb spending. You need to budget and plan accordingly with your finances in the next 12-24 months
  • Avoid jumping to conclusions when you hear things in the media. We can do a full analysis of your mortgage if you reach out to us.  Please call us directly at 604-552-6190 or email trish@primexmortgages.com
  • There are a number of options that we can look at when deciding how to handle future rate increases, whether it is locking in, transferring your mortgage, extending your amortization or consolidating other debts

As we have said before, it is important that you do not panic! Let us help you work out the best strategy for your unique situation.

What to Look for During a Home Tour

General Trish Pigott 12 Jul

Have you found your dream home and can’t wait to check it out in person? Here are a few important things to look for when you go for a home tour.

  1. Odor: Unusual smells can indicate problems such as mold or mildew issues.
  2. Plumbing and Electrical: Check water pressure and electrical systems to ensure there is no erosion or exposed wires. You should also check for a properly functioning HVAC system, sealed water heater, etc.
  3. Noise: This can often be overlooked. Pay attention to any noises in the house, as well as the street and neighbourhood.
  4. Home Layout: Does the layout and function of the home suit your needs?
  5. Number of Rooms: Does the property have enough bathrooms and bedrooms?
  6. Wall and Flooring Condition: What is the condition of the walls and floors? Defects such as warping, cracks, watermarks, etc, can be indicative of larger issues.
  7. Additions or Updates: On occasion, you may go to view a home that was listed as having 2 bedrooms and 1 bathroom, only to find that it actually has an extra bathroom. As great as this might be for your needs, you’ll want to double-check that permits were pulled with the city. Construction done without permits can create issues when it comes to insurance coverage and potential structural headaches if not done professionally.

Remember, things like furniture, decor, wall or floor treatments, and fixtures can be easily updated. These are things that can be changed if the rest of the home suits your needs!

In addition to the above items, there are also a few specific questions you should be asking your realtor. These include:

  1. Is there a deadline for offers?
  2. Have any offers been made?
  3. Why are the sellers moving?
  4. What are the sellers’ preferred possession and completion dates?
  5. Do they have any concerns with the property?

It is important that you work with a professional to ensure that they guide you through the home buying process and find answers to all of the questions above. If you do not have a realtor that you are currently working with, we would be happy to refer you to someone in your area.

As always, we are here if you have any questions. Please reach out to us here or by calling 604-552-6190 or emailing support@primexmortgages.com.

3 Advantages of a Pre-Approval

General Trish Pigott 7 Jul

Mortgage pre-approval means that a lender has stated (in writing) that you qualify for a mortgage. They will specify the term, interest rate and amount you qualify for based on the documentation you submitted of your current income and credit history.

There are three benefits to getting a mortgage pre-approval:

1. It confirms the maximum amount you can afford to spend

People are always tempted to start their search at the top of their budget but it is important to remember that there will be additional fees. Closing costs can range from 1% to 4% of the purchase price. By factoring these into your budget, it can help you narrow down a home that is affordable and ensure future financial stability.

2. It can secure you an interest rate for 90-120 days while you shop for your new home

Getting pre-approved guarantees that the rate offered to you will be locked in from 90 to 120 days. This helps if interest rates rise while you are still shopping. However, if the rates decrease, you would be offered the lower rate.

3. It lets the seller know that securing financing should not be an issue

Lastly, having a pre-approval lets the seller know that you are able to make the purchase. This can be very helpful in competitive markets.

Once your pre-approval is in place, you’ll want to make sure that you do not jeopardize it. It is important that you don’t quit or change jobs, buy a new car, transfer large sums of money between accounts, leave bills unpaid or open up new credit cards.

If you have any questions or want to get your pre-approval started today, don’t hesitate to reach out to us at 604-552-6190 or by applying online here.

Preparing for Property Taxes

General Trish Pigott 24 Jun

It’s that time of year! Property taxes are due on July 4th, 2022 – You must claim your Home Owner Grant (if eligible) by then as well!

Home Owner Grant

The easiest way to apply for your Home Owner Grant is online. This grant is a credit of $570 that will go towards the total amount owing on your property taxes. To get started, you’ll need the jurisdiction and roll number for the property you are applying for. This can be found on the notice that was mailed to you last month, or on your BC Assessment that was mailed in January. Once you have this information, you can use this link here to get started.

If your property taxes are included in your mortgage payments and paid by your lender, you still need to apply for your Home Owner Grant. Your lender cannot do this on your behalf. If you do not claim your grant, you will face a penalty of 5%. If there are still any unpaid balances or unclaimed grants after Thursday, September 1, 2022, you will be charged a second 5% penalty. 

You can learn more about property taxes and the Home Owner Grant here.

If you have questions, we encourage you to call our office at 604-552-6190. We’re always happy to help!

Are You Ready For Home Ownership?

General Trish Pigott 21 Jun

If you think you’re ready for home ownership then this post is for you! Owning a home requires more than stable employment and money for a down payment – Here are a few additional things to consider.

1. You Can Afford Your Down Payment & Ongoing Costs

Once you have the down payment, it is important that you can also manage the monthly mortgage payments and ongoing maintenance that comes with home ownership. Our “My Mortgage Toolbox” app has a great calculator to help you determine what you can afford on a monthly basis. And we are here to help with that as well!

2. You Have Good Credit

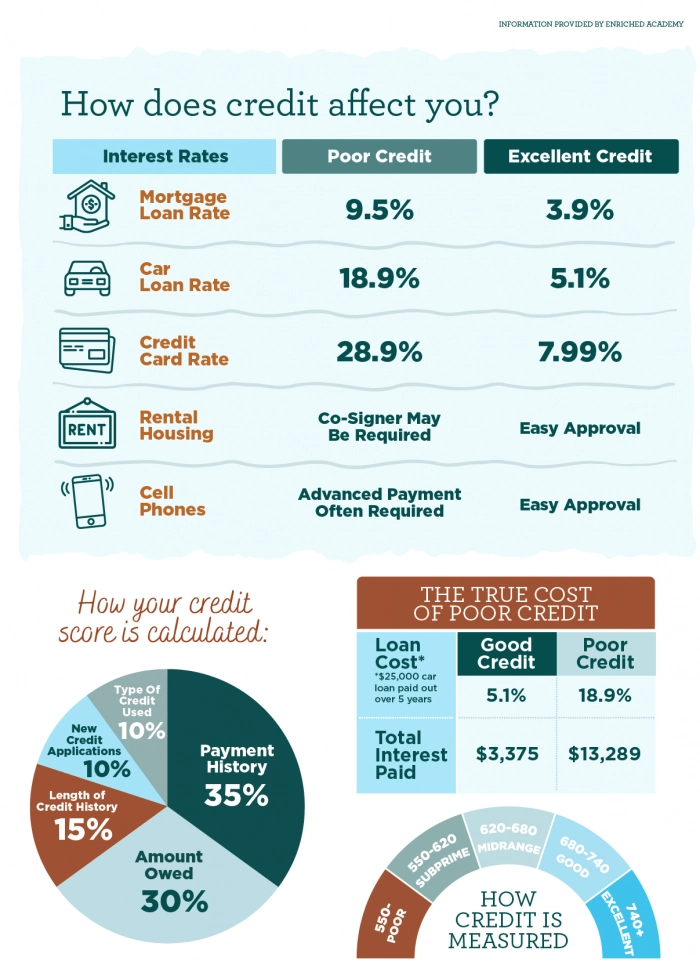
Credit scores play a major role in qualifying for the financing to purchase a home. If you have a good credit score (at least 680) you have nothing to worry about! However, if your credit score is below this, it is more likely that you will be paying higher interest rates or not be able to qualify. Working with a mortgage professional can help get you on the right track as quick as possible. Sometimes all that’s needed is debt consolidation or a few subtle changes.

3. No Other Large, Upcoming Expenses

Do you plan on buying a new vehicle in the next two years? Are you thinking of starting a family? Are you considering going back to school? Although you may think you can afford to purchase a home right now, you have to be honest about your future plans. What does your life look like in one year? Five years? Ten years? Incurring big expenses is something that you need to factor into your budget.

4. You are Disciplined to Budget for Home Ownership

One of the most important factors for purchasing a home is budgeting. You have to know what you can afford and stick with it! It is easy to be tempted by a gorgeous six bedroom home with a backyard pool in a private community – but at what cost? If going all-in is going to leave you scrambling each paycheck or derail any plans of future financial stability, it is worth rethinking. Understanding the difference between what you NEED in a home versus what you WANT is important.

Thank You to Our First Responders

General Trish Pigott 17 Jun

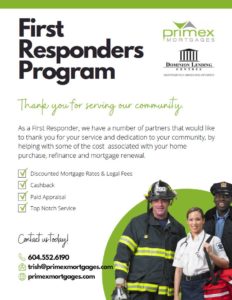
Do you know a First Responder? Perhaps it’s yourself! As a thank you for serving our community, we have teamed up with other industry professionals to help save you money around the costs of purchasing a home or refinancing your current one. Contact our office at 604-552-6190 to find out about our amazing First Responders Program today!

First Responders Program


When Was Your Last Credit Check-Up?

General Trish Pigott 14 Jun

A few simple steps to healthy credit…

Just like you have a physical every year to make sure you’re healthy, you should do the same for your credit score. Here are a few things you should be looking for.

Mistakes

Make sure your personal information is correct and up to date. This includes your date of birth and any other identifying information.

Errors

Even creditors make mistakes, so carefully look over any negative information to confirm that it’s true. They will be required to change any errors that you find.

HINT: If you find an error, send a letter to the credit bureau to make them aware and then send a copy to the credit agency that incorrectly reported it. This will ensure it is taken care of in a timely manner.

Outdated Information

Credit agencies are required to remove information after a specific number of years. For example, if you fall behind on your payments and then correct it, the history showing this is to be removed after 6-7 years. However, it’s important to be proactive and follow up to make sure it gets done.

Fraud

We all know someone who has had their identity stolen and nothing destroys a credit score more than this. Often, it may be someone you know such as a family member or a friend. Make sure you keep your credit information protected, as they may suggest that they just “borrowed” it.

Why do errors on your credit report matter?

Even minor errors like a misspelled name or wrong address can lower your credit score and keep you from getting a loan. This is why it’s important to review it every year and keep it “healthy”. We suggest choosing a day that will be easy to remember, such as your birthday or the day you file your taxes.


Have questions about your credit score? Reach out to us here!

Primex is Celebrating 12 Years

General Trish Pigott 31 May

This has been an exciting month for us! Primex turned 12 on May 1st and we have spent the month celebrating and reminiscing on the last 12 years. We have accomplished so much as a team, receiving numerous awards and recognition in our industry and the community, which has us in the top 2% of mortgage brokers Canada-wide. If you have been a part of our journey, THANK YOU! We could not have gotten here without you.

On May 20th, our team took the day to celebrate at the Glass House Estate Winery in Langley – Wow! It’s beautiful. If you haven’t been, we highly recommend that you check it out. We enjoyed a delicious lunch on the patio, complimented by a wine tasting and wonderful service.

We will be wrapping up our birthday celebrations this weekend at Pitt Meadows Day. This annual event is a community tradition that takes place rain or shine. This year marks the 81st anniversary! It’s being held on June 4th at Harris Road Park in Pitt Meadows where we will have a Primex tent in the field exhibitor’s area. Come say hi for a fun surprise and a chance to win some awesome prizes. It’s been a long time since we have seen our clients in person, so we hope to see you Saturday! You can check out more details for the event here.

Again, we want to extend a huge thank you to everyone who has supported Primex over the years. We love our clients and partners and look forward to many more years together.