|
|
|

|
|
Latest News Trish Pigott 28 Oct
|
|
|
|
|
Latest News Trish Pigott 26 Oct
Recent economic forecasts suggest the Bank of Canada may begin increasing interest rates sooner than originally expected, possibly as early as October 28, with further increases in 2027. While nothing has been confirmed, this means we may not see the lower mortgage rates many homeowners were hoping for.
Variable rates: Could increase over the coming months if the Bank of Canada raises its rate.
Fixed rates: Have remained relatively stable recently, but could still fluctuate based on the economy and bond markets.
Mortgage renewals: If your mortgage is coming up for renewal in the next 6 – 12 months, now is a good time to review your options.
Below is a comparison showing how a 0.25% or 0.50% increase in variable mortgage rates could affect homeowners with mortgage balances of $400,000, $600,000 and $800,000.
Assumptions: Starting rate of 3.50%, 25 years remaining, monthly payments, and semi-annual compounding. Calculations assume payments are adjusted immediately to maintain the 25-year amortization.
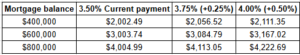
$400,000 mortgage
+0.25% rate increase
$54.03 more per month
+0.50% rate increase
$108.85 more per month
$600,000 mortgage
+0.25% rate increase
$81.05 more per month
+0.50% rate increase
$163.28 more per month
$800,000 mortgage
+0.25% rate increase
$108.06 more per month
+0.50% rate increase
$217.71 more per month
Reminder: Adjustable-rate mortgages generally change payments when rates change. Fixed-payment variable mortgages may instead keep payments unchanged while more goes toward interest and less toward principal, potentially extending the amortization.
Variable mortgage holders: Prepare for the possibility of a 0.50-percentage-point increase over the next several months. Review affordability and payment adjustments now rather than waiting for the Bank of Canada announcement.
Fixed-rate borrowers: Continue comparing three-year and five-year fixed options. There is currently insufficient evidence to conclude that fixed rates will increase significantly in the immediate future.
Homeowners Renewing in 2027: Budget conservatively. The possibility of further rate reductions has weakened, but the evidence does not yet justify substantially increasing our five-year mortgage-rate projections.
The next announcement is October 28, 2026, when the Bank of Canada will announce its interest-rate decision and release updated economic projections.
Reminder: if there is a change, it will be to the Overnight Target Rate which affects the Prime Rate not, Fixed Rates. Fixed Rates could change if the bond market and the dollar are affected so lock in a rate now if you are on the fence or looking at a change to your current mortgage. When in doubt, contact us to lock in your rate.
Our advice? Don’t try to time the market. Time your life and your budget. The lowest rate isn’t always the best mortgage. Choosing the right term, payment structure and flexibility for your personal situation is what matters most.
General Trish Pigott 6 Oct
Based on the Bank of Canada’s latest position, current Canadian bond yields, and the recent change in economists’ forecasts, I would not be telling clients that materially lower mortgage rates are coming in 2027. The environment has changed. Rates are likely entering a “higher-for-longer, but not crisis-level” period, with variable rates potentially drifting upward and fixed rates remaining volatile.
As of September 2, the Bank of Canada is holding its policy rate at 2.25%, with typical prime around 4.45%. The Bank says inflation risks have increased because of energy prices, geopolitical conflict, tariffs and counter-tariffs, even though underlying/core inflation has remained near 2%.
At the same time, the Government of Canada 5-year bond yield was about 3.63% on October 5, which is important because it is a major pricing influence on 5-year fixed mortgages. Canadian lenders have already been responding: the Big Six have recently increased fixed mortgage pricing as bond yields rose.
These are planning ranges, not predictions of specific lender rates. Mortgage pricing depends on borrower type, insurance status, loan-to-value, lender spreads and promotions.
| Year | BoC Policy Rate – planning range | Variable Mortgage – rough range | 5-Year Fixed – rough range | My view |
|---|---|---|---|---|
| 2027 | 2.50–3.00% | 3.6–4.4% | 4.2–5.1% | Rates likely edge higher |
| 2028 | 2.75–3.25% | 3.9–4.7% | 4.1–5.1% | Normalization |
| 2029 | 2.75–3.25% | 3.9–4.7% | 4.0–5.0% | More stable |
| 2030 | 2.50–3.25% | 3.7–4.7% | 3.9–5.0% | Stable/moderate |
| 2031 | 2.50–3.25% | 3.7–4.7% | 3.9–5.1% | “New normal” |
Rates will land roughly around 4.5 – 5.5% as the central planning zone for Canadian mortgage rates over the next five years, we will not see a return to the ultra-low 2–3% fixed mortgages of the pandemic era.
There is significant uncertainty around those ranges. Earlier Bank of Canada market-participant forecasts had the 5-year Government of Canada bond yield around 3.1% at the end of 2027, but the actual benchmark has recently been around 3.6%, illustrating how quickly the outlook has repriced.
The argument for variable mortgages through 2024–26 was straightforward: inflation was falling, the Bank of Canada was cutting, and borrowers could benefit as prime declined.
We are now much closer to the bottom of that rate cycle.
RBC Economics believes rates have effectively bottomed and expects the Bank of Canada eventually to begin raising rates as the economy strengthens. RBC Market-implied forecasts have similarly pointed toward the overnight rate gradually moving from 2.25% toward roughly 2.5–3% over the next several years.
That doesn’t mean variable mortgages are suddenly bad.
In fact, variable is currently attractive because the best discounted variable pricing is below comparable five-year fixed pricing. Current comparison data shows approximately 3.65% variable versus roughly 4.74% for a competitive 5-year fixed, although individual borrowers will see different pricing.
But the reason to choose variable has changed. You’re getting a lower rate today and greater flexibility, but you need to be financially comfortable if prime increases over the next several years.
This surprises clients.
We repeatedly hear:
“The Bank of Canada isn’t increasing rates, so why are fixed rates going up?”
Because the Bank of Canada doesn’t directly price fixed mortgages. Government bond yields and lender funding costs are much more important.
And bond markets have become significantly more concerned about inflation, government borrowing, geopolitical instability and energy prices. Global bond markets recently experienced another major selloff, pushing long-term yields sharply higher.
4 Things to watch particularly closely.
Inflation and energy prices. The Bank of Canada says headline inflation has recently been around 3%, largely because of energy, although inflation excluding gasoline has been closer to 2.2%.
Canada–U.S. trade policy. Tariffs are problematic because they can simultaneously weaken economic growth and increase prices. That puts the Bank of Canada in a difficult position.
Government debt and global bond yields. This is the underappreciated risk for fixed mortgages. Even if Canadian inflation behaves reasonably well, higher global yields can keep Canadian fixed mortgage rates elevated.
Geopolitical instability. Energy supply disruptions and conflict can rapidly change inflation expectations. That’s exactly what markets have been experiencing recently.
When choosing between fixed versus variable, be reminded it’s not about which rate wins.
It is a risk-management decision.
For a financially strong client with good cash flow, emergency savings and tolerance for payment changes, variable can still be very attractive. The current discount relative to fixed gives the borrower some cushion before variable becomes more expensive.
For someone whose budget is tight, particularly a first-time buyer or a household carrying significant consumer debt, I would lean toward fixed or shorter-term fixed. Certainty has value when an extra $200–$400 a month would materially affect the household.
And we think the 3-year fixed deserves particular attention over the next year.
It provides payment certainty through what could be a volatile 2027–28 period without locking someone into today’s environment for a full five years. It gives the borrower another opportunity to reassess in 2029–30.
It’s a smart term to compare with the 5 year fixed rate option to see what the difference is in those rates and terms to determine the best financial choice.
For the last few years the question has often been:
“When are rates coming down?”
We need to shift that thinking toward:
“What mortgage strategy gives you the best combination of rate, flexibility and protection if rates don’t come down?”
For renewals, homeowners should be looking at three scenarios:
Variable: Today’s payment + payment at prime +0.50% and +1.00%.
3-year fixed: Payment certainty with an earlier opportunity to reprice.
5-year fixed: Maximum payment certainty, but with careful attention to penalty structure and flexibility.
When deciding, ask yourself:
“Which of these payments would you still be comfortable carrying if the economy doesn’t cooperate?”
That will help your decision rather than guessing what interest rates will do and lead toward proper mortgage planning.
2027: Slightly higher rates are more likely than significant cuts.
2028–29: Policy rates probably settle somewhere around a neutral 2.75–3.25% range unless Canada enters recession.
2030–31: Mortgage rates probably normalize, but I would still expect conventional fixed mortgage rates broadly around 4–5% rather than 2–3%.
RBC’s current housing outlook similarly says interest rates have likely reached their cyclical bottom and expects some upward pressure on longer-term rates through 2027.
The biggest wild card is recession. A significant Canadian/U.S. downturn would change this forecast quickly: the Bank of Canada could cut rates and bond yields could fall, which would favour variable borrowers and eventually pull fixed rates lower.
But… another inflation shock could push both substantially higher like what we saw in 2022.
Don’t wait for the perfect rate. Build the right mortgage strategy.
For clients buying or renewing in 2027, our advise is that we can not predict the lowest rate and will help you compare options that stress-tests the mortgage against several possible rate environments and chooses the term that best protects the household.
That’s why our goal is to always be Guiding Canadians Home with more valuable conversations rather simply quote rates.
We are here for those conversations so if you want to talk more specifically about your household and mortgage BOOK HERE for a 15 minute phone call.