Recent economic forecasts suggest the Bank of Canada may begin increasing interest rates sooner than originally expected, possibly as early as October 28, with further increases in 2027. While nothing has been confirmed, this means we may not see the lower mortgage rates many homeowners were hoping for.
Here’s what you should know:
-
Variable rates: Could increase over the coming months if the Bank of Canada raises its rate.
-
Fixed rates: Have remained relatively stable recently, but could still fluctuate based on the economy and bond markets.
-
Mortgage renewals: If your mortgage is coming up for renewal in the next 6 – 12 months, now is a good time to review your options.
Example of How Payments Can Be Affected
Canadian Variable Mortgage Payment Comparison
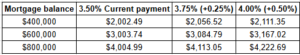
Below is a comparison showing how a 0.25% or 0.50% increase in variable mortgage rates could affect homeowners with mortgage balances of $400,000, $600,000 and $800,000.
Assumptions: Starting rate of 3.50%, 25 years remaining, monthly payments, and semi-annual compounding. Calculations assume payments are adjusted immediately to maintain the 25-year amortization.
How much more would homeowners pay?
$400,000 mortgage
+0.25% rate increase
$54.03 more per month
+0.50% rate increase
$108.85 more per month
$600,000 mortgage
+0.25% rate increase
$81.05 more per month
+0.50% rate increase
$163.28 more per month
$800,000 mortgage
+0.25% rate increase
$108.06 more per month
+0.50% rate increase
$217.71 more per month
Reminder: Adjustable-rate mortgages generally change payments when rates change. Fixed-payment variable mortgages may instead keep payments unchanged while more goes toward interest and less toward principal, potentially extending the amortization.
What Should Home Owners and Home Buyers Prepare For?
Variable mortgage holders: Prepare for the possibility of a 0.50-percentage-point increase over the next several months. Review affordability and payment adjustments now rather than waiting for the Bank of Canada announcement.
Fixed-rate borrowers: Continue comparing three-year and five-year fixed options. There is currently insufficient evidence to conclude that fixed rates will increase significantly in the immediate future.
Homeowners Renewing in 2027: Budget conservatively. The possibility of further rate reductions has weakened, but the evidence does not yet justify substantially increasing our five-year mortgage-rate projections.
The next announcement is October 28, 2026, when the Bank of Canada will announce its interest-rate decision and release updated economic projections.
Reminder: if there is a change, it will be to the Overnight Target Rate which affects the Prime Rate not, Fixed Rates. Fixed Rates could change if the bond market and the dollar are affected so lock in a rate now if you are on the fence or looking at a change to your current mortgage. When in doubt, contact us to lock in your rate.
Our advice? Don’t try to time the market. Time your life and your budget. The lowest rate isn’t always the best mortgage. Choosing the right term, payment structure and flexibility for your personal situation is what matters most.